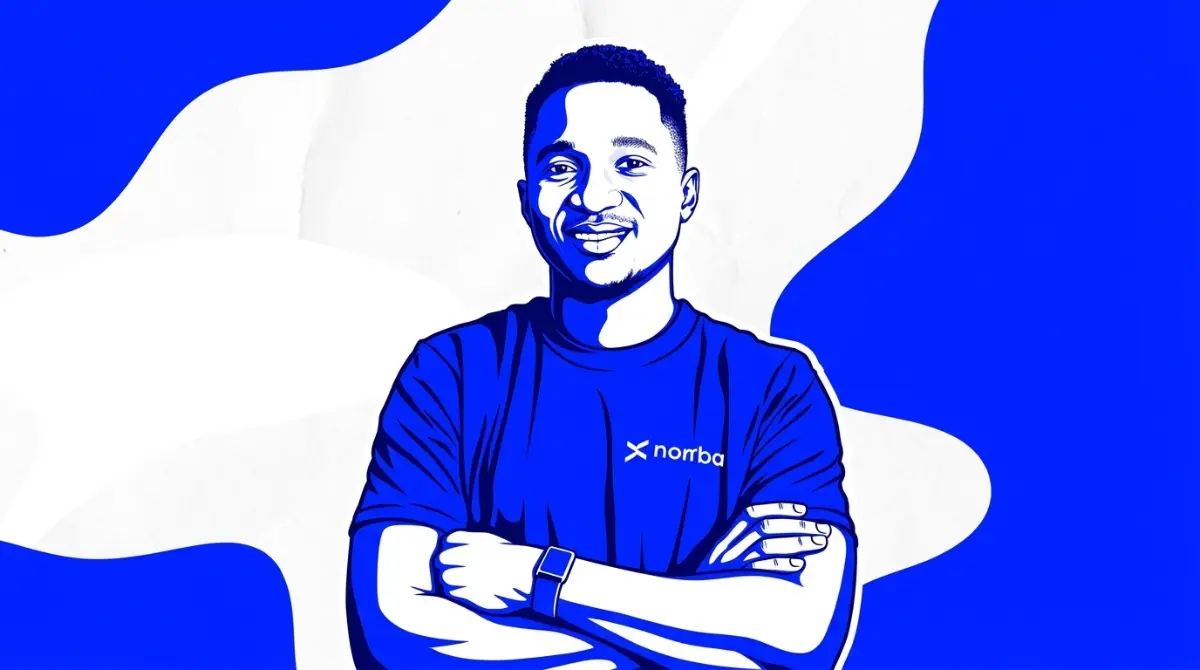


Nomba Expands Congo Payments Network Into Zambia
Nigerian business banking platform Nomba expanded its Democratic Republic of Congo cross-border trade network into Zambia, partnering with domestic financial institutions to let merchants settle agricultural, retail, and wholesale invoices in US dollars or Congolese francs without settlement friction.
Inioluwa Ademidun | · 10 min read
Cross-border commerce between Central and Southern Africa often stalls at physical border posts. Heavy commercial trucks loaded with maize meal, building supplies, processed beverages, and refined copper sit in long lines near Kasumbalesa. Drivers sleep in vehicle cabs for days while commercial banks in Lubumbashi and Kitwe clear paper letters of credit through correspondent accounts in Europe or North America. That broken settlement system ties up working capital for regional distributors, adds currency risk, and slows regional trade. Lagos business finance firm Nomba stepped forward on Friday, October 23, 2026, to address that commercial gridlock. The financial platform confirmed that it extended its commercial settlement network from the Democratic Republic of Congo into neighboring Zambia. The expansion allows Congolese merchants to pay Zambian manufacturers and agricultural wholesalers immediately in Congolese francs or US dollars, with funds arriving in Zambian bank accounts or domestic mobile wallets in seconds. The initiative builds on previous trade finance operations, continuing regional expansion efforts we documented when Nomba secured debt financing for Congo trade.
The geographic move targets one of the fastest-growing trade channels in Africa. Official records published by the Bank of Zambia show that Zambian merchandise sales to the Democratic Republic of Congo reached $1.6B in 2025, climbing by roughly thirty-three percent year-on-year. The trade relationship is driven by geography: the southern provinces of the Congo, including the mineral centers of Katanga, depend on Zambian farms and factories for basic groceries, animal feed, fuel, and heavy machinery parts. Because formal commercial banking between the two nations remains slow and costly, traders have historically relied on informal currency couriers who carry physical cash across dirt roads in duffel bags. Nomba chief executive officer Yinka Adewale pointed out that commercial ambitions to expand intra-African business have outpaced the financial pipes needed to move funds. By building direct settlement connections through licensed Zambian partner institutions, Nomba gives registered businesses a secure digital rail that lowers transaction costs and eliminates courier robbery risks. The regional banking push mirrors cross-border developments we tracked when Yellow Card expanded international settlement rails.
The Structural Pain of the Lubumbashi to Ndola Trade Axis
To grasp why Nomba entered this specific region, one must look at the geography connecting the Copperbelt to Katanga. The industrial mining cities of Lubumbashi and Kolwezi house millions of consumers, yet local agricultural production satisfies only a fraction of municipal food demand. Zambian farmers in Central and Copperbelt provinces produce large agricultural surpluses: yellow maize, poultry, soybean meal, and fresh vegetables: that find eager buyers just across the northern border.
Despite steady commercial demand, financing transactions between both nations has been an operational nightmare. A Congolese wholesale merchant purchasing fifty metric tons of Zambian grain typically faces three bad payment choices. The first choice is using traditional correspondent banking rails: sending funds through international clearing houses in London or New York, an exercise that takes four to seven business days and subtracts up to seven percent in foreign exchange spreads and processing fees. The second choice is finding physical US dollar notes in Kinshasa or Lubumbashi, paying street premiums to black-market dealers, and handing paper money to transport drivers to cross the border manually. If border customs agents seize the cash or highway bandits intercept the vehicle, the merchant loses their entire investment. The third choice is using informal money brokers, whose opaque accounting leaves merchants vulnerable to fraudulent payment receipts. Nomba software replaces these risky methods with an electronic dashboard. When an invoice is issued, the Congolese buyer approves the charge inside their business portal, and the Zambian agricultural cooperative receives verified Zambian kwacha or US dollars instantly, allowing trucks to clear border checkpoints without financial delays. The operational need for transparent business settlement tools was analyzed in our review of Bujeti automated software tools for African finance teams.
The Partner Banking Strategy: Sidestepping Red Tape
A notable operational choice made by Nomba leadership is expanding into Zambia through registered local banking partners rather than waiting for direct commercial licenses. Securing a formal financial institution license from the Bank of Zambia requires millions of dollars in mandatory statutory capital reserves, months of regulatory inspections, and lengthy compliance audits.
Rather than freezing company capital in regulatory escrow accounts, Nomba integrated its software with established Zambian commercial banks and licensed payment clearing houses. Nomba provides the front-end business application, invoice generation tools, and currency exchange engine, while the licensed partner bank handles local settlement, domestic clearing house transfers, and regulatory compliance reporting to the Bank of Zambia. This partnership structure allows the fintech to launch operations in weeks rather than years, preserving capital to hire local customer service representatives and onboarding specialists. The strategy reflects how agile financial platforms scale across diverse jurisdictions without taking on heavy balance sheet overhead. The operational balance between partner banking and direct regulatory compliance matches approaches we detailed when Airtel Money updated compliance structures ahead of international listings.
Comparing Central African Cross-Border Settlement Options
| Settlement Method | Average Clearing Speed | Transaction Fee Range | Supported Payout Options | Operational Risk Profile |
|---|---|---|---|---|
| Nomba Trade Network | Under two minutes (Real-time) | 1.5% to 2.5% fixed transparent rate | Zambian bank accounts & mobile wallets | Secure electronic verification with audit logs |
| Traditional SWIFT Rail | 3 to 7 business banking days | 4% to 8% plus correspondent deductions | Formal commercial bank accounts only | Safe but slow; ties up inventory capital |
| Physical Cash Couriers | 12 to 48 hours road travel time | 3% to 6% broker and transport fee | Physical paper bills handed to suppliers | Severe danger of road theft and border seizure |
| Informal Hawala Networks | 2 to 6 hours confirmation window | 5% to 10% unregulated spread | Local merchant cash pickup points | No legal recourse in disputes; fraud exposure |
The operational comparison demonstrates why digital business tools are displacing traditional channels. By combining real-time clearing with low transparent fees, Nomba removes the financial penalty that has long burdened intra-regional trade. Zambian food suppliers can confirm payment on a smartphone before warehouse workers load transport trucks, eliminating credit defaults and reducing transit disputes.
From Kudi Agent Networks to Pan-African Business Banking
The geographic expansion into Central Africa illustrates a major transformation in Nomba corporate journey. Founded in 2017 by Yinka Adewale and Pelumi Styles as Kudi, the startup began as an agency banking network in Nigeria. Kudi deployed point-of-sale terminals to neighborhood kiosks, allowing citizens without bank branches to deposit paper cash, withdraw money, and pay electricity bills.
While agency banking provided strong transaction volume, retail POS operations in Nigeria became fiercely competitive, with margins shrinking under central bank fee caps and rising hardware costs. In 2022, management rebranded the enterprise as Nomba, shifting strategic attention toward complete business banking. Instead of serving only neighborhood retail agents, the platform began courting commercial distributors, restaurant chains, and import companies. The company expanded into inventory tracking, payroll software, corporate debit cards, and multi-currency business accounts. Entering the Democratic Republic of Congo earlier this year marked the fintech first major international move, proving that its software tools could solve merchant problems outside West Africa. Moving into Zambia represents the logical next step: following the money flows of existing Congolese clients directly into supplier hubs. Corporate strategy shifts among West African financial platforms match patterns we followed when Remita expanded consumer payment services.
Managing Currency Volatility Across Two Fragile Currencies
Operating a financial bridge between Kinshasa and Lusaka requires managing severe currency volatility. Both the Congolese franc and the Zambian kwacha have experienced periods of rapid currency depreciation, driven by copper price swings, debt restructuring talks, and domestic inflation.
If a Congolese buyer pays in francs and the currency slides by five percent before the Zambian supplier receives kwacha, one of the parties absorbs a painful loss. Nomba solves this currency friction by using real-time treasury hedging. When a transaction is initiated, the platform locks in the foreign exchange conversion rate for fifteen minutes, guaranteeing the payout amount to the Zambian vendor regardless of sudden market movements. The system maintains liquid US dollar reserves in regional accounts, allowing merchants to settle contracts in hard currency if international suppliers demand dollar pricing. By insulating small business owners from sudden currency drops, Nomba gives regional traders the price predictability needed to sign long-term supply agreements. The macroeconomic challenges of navigating currency risks across emerging markets were explored in our analysis of Onafriq restructuring agency operations.
Future Roadmap: Working Capital, Deposits, and Trade Credit
Payment settlement is merely the starting point for Nomba regional ambitions. Adewale confirmed that the company plans to secure a fresh equity funding round in coming months to support its balance sheet expansion across Central and Southern Africa.
Over time, the platform aims to provide working capital credit, trade insurance, and interest-bearing business deposits to merchants operating on the cross-border route. In commercial trade, suppliers often wait thirty to sixty days for retail buyers to sell inventory before receiving final payment. A Zambian maize exporter who sells fifty thousand dollars in grain to a Congolese supermarket chain cannot buy seeds for the next planting season while waiting for invoices to settle. Nomba intends to deploy invoice factoring tools: advancing eighty percent of the invoice value to the Zambian supplier immediately, then collecting the full balance from the Congolese merchant upon inventory sale. Because Nomba software monitors merchant daily sales receipts, the platform can underwrite trade loans with far greater precision than traditional commercial banks. The growing availability of specialized trade credit was examined in our report detailing ThriveAgric issuing debt paper for agriculture.
The African Continental Free Trade Area in Practice
Political leaders across the continent frequently deliver speeches celebrating the African Continental Free Trade Area, promising that reducing tariffs will spark an era of industrial prosperity. Yet business owners on the ground understand that cutting import tariffs means little if cross-border financial rails do not exist.
A manufacturer cannot sell products to a neighboring nation if receiving payment takes a week of paperwork and costs ten percent in bank fees. While diplomatic delegations meet at international trade summits, technology ventures like Nomba are building the actual digital machinery that makes intra-African trade possible. By connecting the banking systems of Central and Southern Africa with accessible software interfaces, fintech platforms are turning political trade agreements into everyday commercial reality. The broader economic momentum across emerging African technology centers reflects milestones we documented when African tech ventures reported strong quarterly funding, alongside foundational regulatory updates tracked when South Africa opened payment rails to fintech companies.
The Long Term Outlook for Cross-Border African Finance
Nomba expansion into Zambia proves that the future of African financial technology lies beyond domestic consumer apps. The early fintech wave was characterized by hundreds of local consumer payment wallets that fought over peer-to-peer transfers inside single countries, resulting in market saturation and thin profit margins.
The modern era belongs to platforms that solve complex B2B trade bottlenecks across international borders. By linking Congolese buyers directly to Zambian suppliers, Nomba has positioned itself at the center of a vital trade artery that moves millions of dollars in real goods every week. As Yinka Adewale and his team deploy capital, secure trade partnerships, and expand lending products, they are demonstrating that commercial value is created by removing physical and financial friction for everyday entrepreneurs. In the unfolding story of African economic integration, the true champions will be the builders who lay down the digital tracks that allow goods, money, and opportunity to move freely across the continent.
Read More on TechRobust:
Inioluwa Ademidun
 LinkedIn
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.