

Verto and Visa Launch Corporate Cards for African Markets
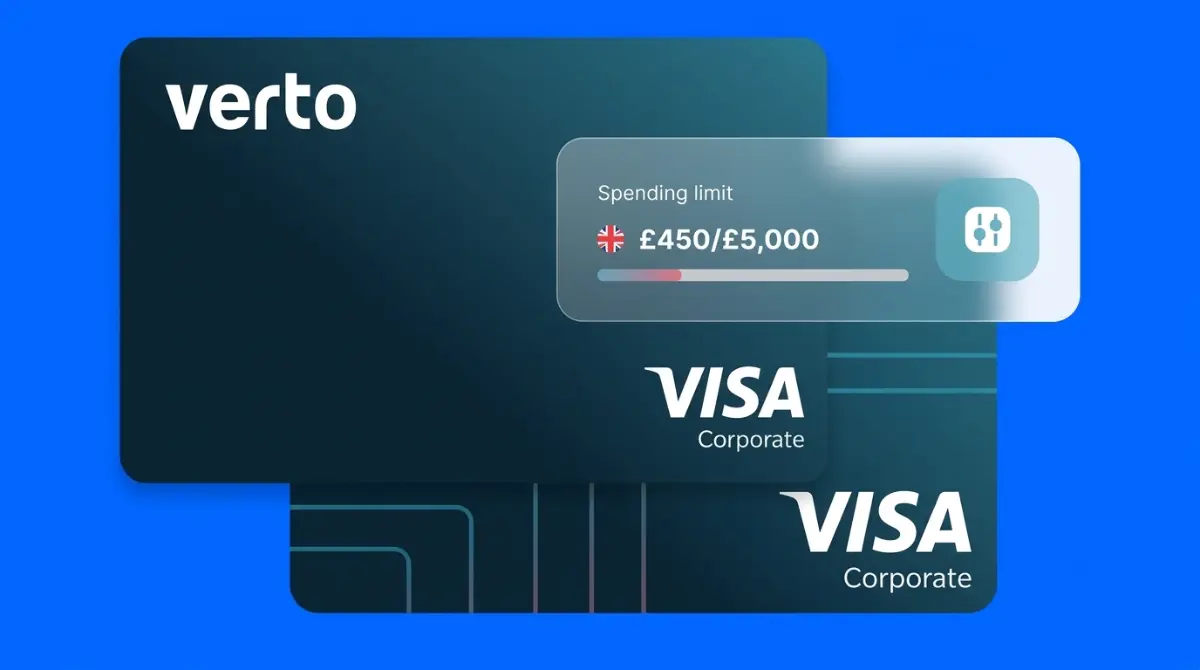
Verto partnered with Visa to introduce multi-currency corporate cards, allowing African companies to process international payments while avoiding heavy foreign exchange penalties.
Inioluwa Ademidun | 22 Sept. 2026 · 8 min read
For years, financial isolation forced African founders to operate at a severe disadvantage. When a technology company in Lagos or Nairobi wants to pay for basic internet infrastructure, cloud hosting, or digital advertising, they hit an invisible wall. Traditional banks force them to convert their local currency into American dollars or British pounds at punishing exchange rates. Even worse, many international software vendors simply reject African payment methods entirely. Verto just announced a partnership with Visa that directly attacks this exact banking inequality by issuing multi-currency corporate cards.
African businesses have suffered from poor financial infrastructure for decades. The standard banking system forces them to use single-currency cards. When an executive tries to pay a European supplier, the local bank charges a massive, undisclosed markup to process the conversion. Sometimes, the transaction fails completely because the card operates on prepaid rails that global merchants refuse to accept. This friction causes active harm to the bottom line.
Verto operates as a business-to-business global payments platform. By teaming up with Visa, they created a virtual corporate card that holds and settles funds in eleven different global currencies simultaneously. Users can transact directly in American dollars, euros, British pounds, Japanese yen, and several other major currencies without paying a foreign exchange penalty. If the company holds euros in their wallet, the card pays the merchant in euros. The entire conversion process disappears. Ola Oyetayo, the chief executive officer and co-founder of Verto, noted that existing card products actively underserve African operators by locking them into single currencies and hitting them with hidden fees.
Breaking Down the Financial Borders
The physical reality of cross-border commerce requires reliable financial pipes. When a travel agency in Nigeria books a hotel in London, they cannot wait three days for a standard bank wire to clear. The client needs immediate confirmation. Before this Visa partnership, companies relied on fragmented payment systems. They maintained multiple bank accounts across different countries, paying monthly maintenance charges for each one. The new Verto card consolidates all these accounts into a single digital interface.
Visa brings its massive commercial network to the table. The card works at roughly 150 million merchant locations worldwide. While the system natively holds eleven major currencies for zero-fee transactions, the underlying Visa infrastructure provides indirect access to 160 additional currencies. This massive reach means an African software firm can pay freelance developers in South America or buy manufacturing parts from Asia using the exact same card. The company guarantees high payment acceptance rates, removing the anxiety of a declined purchase at checkout.
We recently examined how local financial technology companies are securing heavy capital to solve regional banking problems. For example, regional operators are heavily investing in digital banking expansion across the continent to bypass legacy institutions entirely. Verto is taking this same aggressive approach to corporate spending by building parallel infrastructure outside the traditional banking system.
The Geopolitics of Corporate Spending
You cannot separate corporate banking from global geopolitics. Western financial institutions have historically treated African transaction volume with heavy suspicion. They impose strict capital controls and require endless compliance documentation, effectively shutting young startups out of the global economy. By securing a direct partnership with Visa, Verto sidesteps this historical bias. They grant African founders the exact same purchasing power and financial mobility enjoyed by their peers in Silicon Valley or London.
The economics of international software subscriptions highlight this divide perfectly. Running a modern business requires access to cloud hosting, customer relationship software, and digital marketing platforms. These American and European vendors bill exclusively in hard currencies. When an African business owner pays their monthly hosting bill using a local debit card, the bank applies an aggressive currency conversion margin. The business bleeds capital simply to maintain their basic internet infrastructure. Verto stops this financial drain by allowing the company to fund their wallet exactly when the exchange rate is favorable, hold the money in foreign denominations, and spend it later without incurring additional penalties.
Security and System Architecture
Corporate spending requires intense security protocols. Giving employees access to company funds usually ends in lost capital unless strict rules are applied. Verto addressed this by abandoning physical plastic entirely for the initial rollout. The platform generates virtual Visa debit cards instantly upon approval. Because no physical plastic exists, the risk of a thief stealing the card from a wallet drops to zero.
Administrators maintain total control over the spending software. They can instantly freeze a card, terminate an account, or set strict financial limits from a central digital dashboard. The software also allows administrators to restrict purchases based on specific dates, times, and exact merchant categories. If an employee tries to buy concert tickets using a card restricted strictly for office supplies, the system blocks the transaction immediately. The cards also require 3D Secure verification for online purchases, adding an extra layer of identity confirmation before releasing the funds.
The engineering team at Verto is currently building mobile wallet integrations. Soon, users will link these virtual cards directly to their smartphones. This addition will allow business travelers to use contactless payment terminals at airports and restaurants globally, completely replacing the need for carrying foreign cash during business trips.
Operating a financial platform across different jurisdictions requires careful navigation of local laws. Central banking authorities are actively targeting payment regulations to control market concentration, forcing operators to maintain perfect compliance records. Verto handles all the heavy regulatory lifting on the backend, ensuring that every transaction meets international anti-money laundering standards while keeping the user experience completely clean.
Building a Card Infrastructure Network
Verto is not stopping at direct consumer issuance. The company plans to turn its internal architecture into a service for other financial technology firms. They call this the Atlas infrastructure. Soon, they will offer a Cards-as-a-Service model to the broader African startup ecosystem.
Building a credit or debit card program from scratch is an incredibly difficult engineering and legal challenge. A new startup would have to negotiate directly with global networks like Visa, hire teams of compliance lawyers, and build secure server connections to handle transaction processing. Verto wants to rent out their established infrastructure. A young financial startup in Ghana or Senegal could use the Atlas system to issue custom branded corporate cards to their own user base. Verto handles the complicated banking rails, while the new startup focuses strictly on acquiring customers and building their brand.
This white-label arrangement expands the total addressable market for Verto exponentially. They transition from being a simple corporate wallet into a foundational layer of the African financial internet. Other applications will build their business models entirely on top of the Verto payment processing engine.
A New Era for Emerging Market Founders
The introduction of this multi-currency card signals a maturing phase for African commerce. Startups on the continent are no longer fighting just to survive local economic conditions. They are building ambitious organizations that demand access to the exact same software tools, supply chains, and global markets as their international competitors.
Visa recognized this shift. By extending their commercial rails to partner with Verto, the American credit giant acknowledges that the next massive wave of transaction volume will originate from emerging markets. They want a cut of every payment passing between African importers and Asian manufacturers. Verto serves as the perfect trusted bridge to connect these previously isolated economies.
African founders are tired of asking for permission to participate in international trade. They are tired of hiding behind third-party payment processors or paying extortionate banking fees simply to buy a plane ticket or pay a foreign contractor. This partnership removes the final technical barrier to global expansion. The financial plumbing is finally installed, and the funds are ready to move.
To capture the widest possible user base, Verto constructed a highly transparent pricing structure. Legacy banking institutions hide their profit margins deep inside the currency conversion math. Verto charges a clear monthly fee based on the size of the organization. They offer a free entry tier for young companies just getting started, while larger operations pay up to $50 a month for advanced features and higher transaction limits. When a company funds their card with local currency, they pay a flat percentage fee, but the actual cross-border spending incurs zero markup above the standard Visa exchange rate. This predictability allows chief financial officers to accurately forecast their monthly expenses without fearing sudden spikes in banking costs.
The competition in the corporate card space is heavily aggressive. Western companies like Ramp and Brex dominate the North American market, but they avoid the African continent entirely due to the heavy regulatory friction and volatile local currencies. Verto recognized this massive blind spot. By doing the hard work of securing regional banking licenses and building a custom foreign exchange engine, they captured a market that the American giants ignored. As digital commerce continues to spread rapidly across the global south, the demand for reliable cross-border payment tools will only multiply.
The days of operating a multi-national business out of a single, highly restricted bank account are permanently over. Financial software is eating the legacy banking model. Verto and Visa just handed African companies the keys to the global economy. How these businesses choose to use that newfound purchasing power will dictate the economic future of the continent for the next twenty years.
Read More on TechRobust:
Inioluwa Ademidun
 LinkedIn
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.