

Vesta Secures $30M Series B to Automate Home Mortgage Files
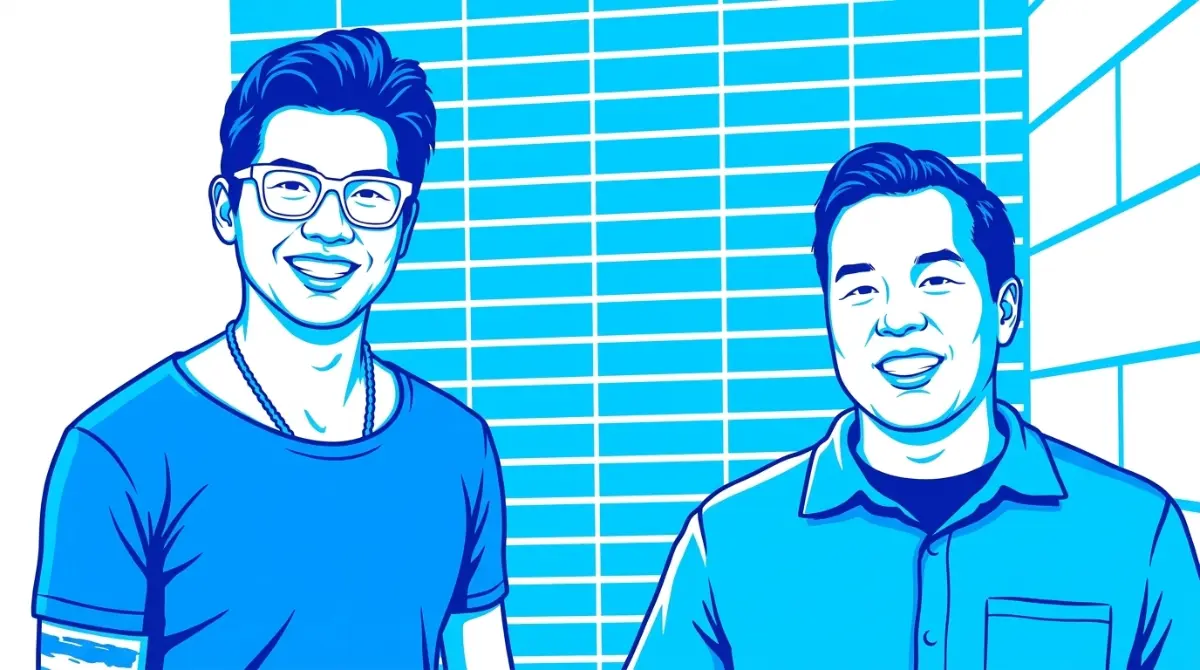
Mortgage software developer Vesta raised $30M in Series B financing led by Conversion Capital with backing from PennyMac and New American Funding, deploying autonomous worker groups to clear residential loan paperwork.
Inioluwa Ademidun | 8 Oct. 2026, 1:30 PM · 7 min read
Processing a residential mortgage in America remains slow, paper-choked, and shockingly expensive. Borrowers hand over tax forms, pay stubs, bank ledgers, and property assessments, only to wait forty days while human loan specialists check document lines by hand. According to data tracked by the Mortgage Bankers Association, originating a single residential home loan costs lenders roughly $11,000, with human labor consuming the vast majority of that total. When interest rate changes squeeze mortgage volumes, lending companies face sharp financial pain from bloated back-office payrolls. San Francisco mortgage infrastructure developer Vesta aims to rewrite that balance sheet reality. The financial software venture completed a $30M Series B funding round, lifting its total capital raised to $85M. The financing round was led by Conversion Capital, with equity participation from mortgage lenders New American Funding, PennyMac Financial Services, and NBKC Bank, alongside Citi Ventures, FirstKey Mortgage, Navitas Capital, Andreessen Horowitz, Zigg Capital, and Parker89. The capital injection arrives as lenders turn to automated systems, an operational shift we tracked when Valon reached a $2.3B valuation to expand mortgage servicing platforms.
The strategic foundation of the investment reflects direct market adoption. Unlike conventional enterprise software rounds where outside venture capital funds gamble on unproven sales pipelines, three of the major financial institutions investing in Vesta already use the platform to originate loans. Chief executive officer Mike Yu confirmed that annual corporate revenue expanded twelve-fold over the preceding year, even while Vesta overall market footprint sits below five percent of nationwide volume. The mortgage lenders running their origination software on the platform process over $100B in annual residential home loans. The platform allows loan desks to replace fragmented legacy interfaces with an automated loan origination system, where software agents examine documents, cross-check income calculations, clear title stipulations, and prepare closing packages. The demand for automated clerical systems across corporate lending mirrors trends we evaluated when Numeral raised $100M to automate financial compliance.
Replacing Patchwork Pipelines With Unified Loan Systems
To grasp why mortgage lenders are buying into Vesta, one must look at the tangled software infrastructure that has paralyzed mortgage lending desks for twenty-five years. Most American mortgage shops run on legacy databases engineered in the late 1990s. These ancient applications were built as basic digital storage cabinets rather than flexible computational engines. If a loan officer wants to verify employment history or check flood zone disclosures, they must copy borrower numbers manually between six disconnected web portals.
This fragmentation produces endless clerical bottlenecks. When a borrower uploads a revised tax return, the file sits inside an unread email inbox until an intake clerk notices the attachment and uploads it to the repository. Vesta replaces that brittle setup with a modern, cloud-native loan operating engine. Around forty percent of all administrative tasks running through the system are executed autonomously without human intervention. The software ingests loan paperwork, verifies numbers against tax databases, and flags discrepancies in minutes. Removing human data entry from the origination cycle cuts processing delays, allowing mortgage lenders to close home loans in days rather than weeks. How modern software architecture displaces legacy financial rails was examined in our report detailing SAP launching native business payment tools.
Long Context Processing and Complex Instructions
The technical breakthrough that made these automated workflows dependable was the arrival of models capable of following complex instructions over long text sequences. Yu credited Claude Sonnet 4.5 as a major turning point for the startup engineering team. Earlier conversational models struggled with mortgage underwriting because residential loan packets frequently span hundreds of pages of complex legal disclosures, bank statements, and tax forms. Smaller models would lose track of details or invent numbers when reading messy financial records.
Claude Sonnet 4.5 demonstrated the capability to follow detailed instructions across complex loan files without wandering off track. Vesta engineers can configure deterministic rules for secondary mortgage investors like Fannie Mae and Freddie Mac, knowing the software will audit every debt-to-income calculation against exact underwriting matrices. If an applicant displays fluctuating self-employment earnings, the software calculates historical cash flow trends and checks whether the numbers meet Fannie Mae liquidity guidelines. This consistency gives credit risk committees the assurance needed to let software handle initial file approvals. We followed how modern reasoning systems execute complex business processes in our analysis of Anthropic releasing Claude Sonnet with sharp cost reductions.
The Moral and Regulatory Stakes of Automated Underwriting
Handing residential mortgage assessments over to automated software introduces serious legal and social considerations. Across American history, homeownership served as the primary vehicle for generational wealth creation, yet discriminatory lending practices like redlining locked minority neighborhoods out of fair credit for decades. If automated models ingest historical lending data, they risk learning and reinforcing past biases under the guise of neutral math.
In Europe, automated credit evaluation systems are placed directly into the high-risk category under the European Union AI Act, requiring exhaustive bias audits, human oversight layers, and transparent explanations for every denied application. While American mortgage laws do not yet include an identical statutory framework, federal agencies like the Consumer Financial Protection Bureau warned that lenders cannot hide behind software to evade fair lending laws. If an automated tool denies a credit application, the lender must provide the borrower with specific adverse action notices explaining the exact financial reasons. Vesta addresses this statutory risk by making every agent decision inspectable. Human underwriters can review the exact calculations and source documents that led to a decision. Maintaining strict audit trails protects lenders from regulatory fines, a challenge we explored when Defeating Volatility in a Cyclical Housing Market
The economic pressure driving lender interest in Vesta is the cyclical reality of the residential housing market. When interest rates drop, mortgage applications surge, forcing lenders to hire thousands of temporary processing workers to clear loan files. When rates climb, application volumes collapse, forcing those same mortgage firms to execute painful mass layoffs to keep from going bankrupt. This cycle makes managing a profitable lending business difficult. Automated software offers lenders a flexible cost base that adjusts to transaction volume. Instead of paying fixed employee salaries during quiet winter seasons, mortgage shops pay for software execution as files move through the pipeline. When home sales spike in the spring, the automated system handles thousands of additional loan files without requiring the human resources department to recruit new workers. Scaling processing capacity without expanding fixed payrolls provides a strong economic shield against volatile housing cycles. The financial realities of software automation across traditional industries match patterns we documented when corporate technology deployments freed thousands of administrative work hours. Despite rapid revenue growth, expanding into hundreds of regional credit unions and mortgage banks involves long enterprise sales cycles. Replacing a core loan origination system is one of the most painful operational surgeries a lending bank can perform. The origination platform touches credit bureaus, title companies, appraisal portals, flood insurance databases, and warehouse lending lines. A botch during system migration can halt daily loan closings, costing the institution millions in lost fees. Convincing conservative risk officers to rip out older tools like ICE Mortgage Technology Encompass requires endless security reviews and compliance certifications. Vesta must prove that its cloud system maintains total data isolation, ensuring customer records and credit histories are protected from outside access. Furthermore, the company must demonstrate that its system uptime remains reliable during peak month-end closing days when thousands of title settlements occur simultaneously. Protecting institutional financial databases against unauthorized access was examined in our report detailing the Revolut data breach involving fake government requests. The $30M Series B financing secured by Vesta demonstrates that the wave of software automation has reached the backbone of American consumer finance. The era of requiring twenty human clerks to manually re-type numbers from PDF tax forms into thirty-year-old databases is drawing to a close. As mortgage originators battle rising customer acquisition costs and compressed lending margins, companies that automate routine paperwork will outcompete lenders reliant on slow manual operations. By pairing modern cloud systems with dependable automated reasoning models, Vesta is turning the forty-day mortgage process into a fast, transparent transaction. The long-term challenge will center on proving that automated loan assessments remain fair, transparent, and compliant through different credit cycles. If Vesta can reduce origination costs while helping everyday families secure home financing without delays, it will establish itself as a foundation of modern American real estate finance. Read More on TechRobust:Enterprise Integration Hurdles and Customer Retention
The Future of American Home Lending
Inioluwa Ademidun
 LinkedIn
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.