

Apple Pay Class Action Certified Over Billion Dollar Fees
A federal judge has certified a class-action lawsuit allowing thousands of American banks and credit unions to challenge Apple over lucrative mobile payment transaction fees.
Umar Thariwat | 25 Sept. 2026 · 8 min read
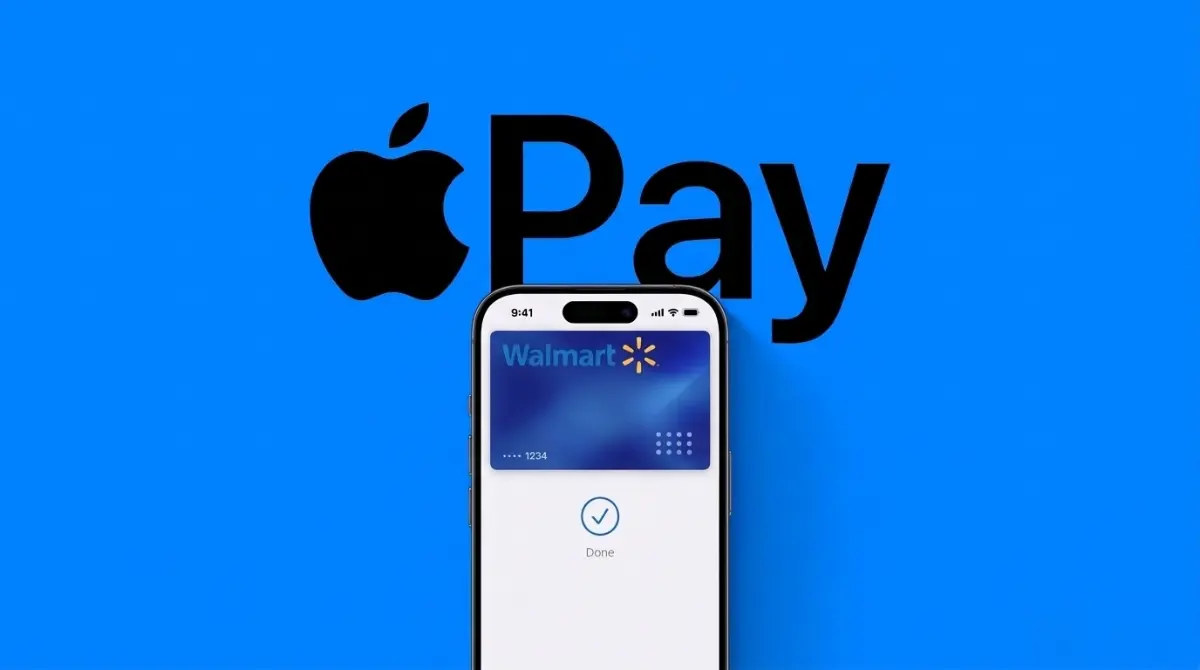
Corporate control over mobile financial transactions is facing intense legal scrutiny. For years, Apple maintained strict authority over the contactless payment hardware inside its smartphones. By restricting third-party access to the Near Field Communication chip, the hardware manufacturer ensured that any consumer tapping their device at a retail checkout counter had to process the transaction through its proprietary wallet application. That technical exclusivity allowed the company to mandate specific transaction fees from financial institutions processing those consumer payments. Now, a massive coalition of regional banks and credit unions is bringing a collective legal challenge against that financial structure.
United States District Judge Jeffrey S. White officially certified a class-action antitrust lawsuit against Apple this week. The certification order, issued on September 23, 2026, allows thousands of domestic payment card issuers to pool their claims into a unified legal offensive. The lawsuit alleges that the technology giant exploited its hardware monopoly to extract supracompetitive fees from financial institutions. The plaintiffs argue that these mandatory payments violate federal antitrust laws, citing competitive mobile environments where similar transaction processing costs nothing for the card issuer.
The legal action originated in 2022 when Affinity Credit Union, GreenState Credit Union, and Consumers Co-op Credit Union filed the initial complaint. The institutions claimed that Apple unlawfully blocked rival software wallets from utilizing iPhone payment hardware, creating a closed ecosystem where financial providers had no alternative but to accept the imposed fee structure. The court appointed law firm Hagens Berman as co-class counsel, noting the firm possesses the necessary antitrust experience to represent the vast collection of financial entities that paid these charges.
The Economics of Mobile Transactions
The financial scale of this legal dispute is massive. Whenever an iPhone user completes a purchase using a linked credit card, the issuing bank must surrender a percentage of the transaction value back to the hardware maker. According to the court filings, the mandated fee sits at 0.15 percent for credit card purchases. This translates to a $1.50 charge on a $1,000 retail transaction. For debit card transactions, the fee is a flat half-cent per use.
While those individual fractions of a cent appear small, they compound rapidly across millions of daily consumer interactions. Legal representatives for the plaintiffs estimate that the technology firm generates up to $1B annually strictly from these issuer fees. The financial institutions argue that these charges are entirely artificial, sustained only by the lack of direct hardware competition on the operating system.
The plaintiffs explicitly compare this pricing model to rival mobile operating systems. Financial institutions pointing to Google Android note that the competing platform supports multiple digital wallets and allows developers to access the underlying payment hardware without charging the card issuers any transaction toll. The lawsuit suggests that if Apple allowed third-party wallets like PayPal or individual banking applications to access the iPhone payment chip directly, open market competition would instantly eliminate the mandatory percentage fee.
This scrutiny over secondary revenue streams reflects broader regulatory pressure on corporate platform gatekeepers. We have seen similar legal confrontations regarding digital storefronts, as documented when Apple appealed an App Store contempt finding to the Supreme Court. When a single corporation controls the only digital entry point to hundreds of millions of consumers, the fees imposed on third-party businesses face relentless legal and political friction.
Monopoly Power and Hardware Exclusivity
The core legal argument centers on whether controlling the hardware access constitutes an illegal aftermarket monopoly. In a previous ruling in 2023, the federal court allowed the primary monopolization claims to proceed while dismissing a separate allegation that the company unlawfully tied its hardware devices to its software wallet. The current certification order reinforces the plaintiffs' position by denying a motion from the defense that attempted to exclude expert testimony. The judge ruled that the plaintiffs' expert testimony successfully established common proof that the hardware manufacturer maintains monopoly power within the specific tap-and-pay mobile wallet sector.
By preventing financial institutions from building their own direct tap-to-pay applications, the plaintiffs claim Apple stunted mobile transaction advancements. The financial institutions argue that an open hardware environment would lead to better transaction security features and increased merchant acceptance, directly benefiting the consumer base. Instead, banks are forced to surrender a portion of their revenue just to ensure their customers can use modern checkout hardware.
This intense focus on corporate service revenue arrives as hardware sales face macroeconomic headwinds. Extracting recurring service fees from third-party partners is a necessary corporate strategy for sustaining financial growth. The financial markets watch these service metrics closely, a pattern observed when Apple App Store changes boosted revenue margins. Any legal threat to a billion-dollar recurring revenue stream demands immediate corporate defense.
The Banking Sector Fights Back
For regional credit unions and small community banks, absorbing unexpected transaction costs directly affects their ability to offer competitive consumer lending rates. Large multinational banks might possess the financial volume to absorb a 0.15 percent margin hit, but smaller institutions operate on razor-thin profitability margins. When a community bank issues a credit card, it relies on standard merchant interchange fees to cover the costs of fraud protection, customer service, and rewards programs. Surrendering a portion of that interchange revenue to a technology company simply because the customer used a mobile phone instead of a plastic card creates an unsustainable financial drain.
The lawsuit details how the technology giant explicitly forbade banks from passing these specific fees down to the consumers. Financial institutions could not add a surcharge to mobile transactions to recoup their costs, forcing them to absorb the financial penalty entirely. This strict contractual control meant the platform operator could dictate terms to the entire American banking sector without facing direct consumer backlash. Customers enjoyed the smooth digital checkout experience, completely unaware that their local bank was paying a hidden premium to facilitate the transaction.
By pooling their legal resources through this certified class action, smaller financial institutions are finally matching the legal firepower of the hardware giant. This collective action is a required strategy when facing massive corporate defendants who can afford to drag individual lawsuits out for decades. The financial sector is signaling that it will no longer passively accept unilateral billing terms from technology platforms, a shift in corporate negotiating power that could influence future agreements over digital identity verification and biometric security integration.
Recent Policy Adjustments and Future Impact
Interestingly, the closed payment ecosystem that prompted this massive legal challenge is already undergoing major structural changes. Facing intense regulatory pressure from the European Union and other international competition authorities, Apple recently altered its developer guidelines. Starting with the iOS 18.1 software release, the company began allowing external software developers to access the secure element inside the phone, enabling third-party applications to offer direct contactless payments.
This updated policy is rolling out across multiple global jurisdictions, including the United States, Canada, Australia, Japan, and the United Kingdom. While this technical concession addresses the primary functional complaint moving forward, it does not erase the financial damages accumulated over the past decade. The certified class-action lawsuit seeks total reimbursement for all the transaction fees previously paid by the card issuers, along with a permanent federal injunction to prevent the company from reinstating the challenged billing policies in the future.
The outcome of this litigation will likely redefine how mobile platforms monetize digital financial tools. The case highlights a growing consensus among regulators and commercial partners that controlling physical smartphone hardware does not grant a company the right to tax every secondary financial service running on the device. Similar disputes over proprietary technical constraints continue to surface across the industry, echoing tensions seen when OpenAI blamed Apple iCloud policy in a separate trade secret lawsuit.
A Waiting Game for Financial Institutions
The certification of this class action is a major procedural victory for the banking sector, but it does not represent a final verdict on the antitrust allegations. The ruling simply confirms that the thousands of affected financial institutions possess enough common grievances to sue as a single entity. The federal court has not yet ruled on whether the mandatory fees actually violate statutory antitrust provisions, nor has it determined if any financial damages are owed.
The defense team will likely pursue a vigorous trial strategy, arguing that its closed payment architecture provides superior consumer security and privacy protections compared to fragmented open systems. The hardware maker has historically maintained that its proprietary transaction routing prevents fraud and justifies the required service fees.
As the legal discovery phase advances and the trial approaches, thousands of American banks and credit unions will watch closely. If the plaintiffs secure a victory, it could force the immediate return of billions of dollars to regional financial institutions. More importantly, it would set a binding legal precedent that limits how dominant mobile operating systems extract revenue from the banking sector. The era of hardware manufacturers operating as unavoidable toll collectors on consumer spending is facing its most consequential legal test to date.
Read More on TechRobust:
Umar Thariwat
 LinkedIn
Umar Thariwat
Expertise:Tech News Reporting, Tech Business Analysis, Economic Foundations, Market Trends, Digital Economy
Award:Rising Voice of the Year 2025
Thariwat is a Staff Writer and Reporter covering tech news and enterprise trends at TechRobust. Blending daily reporting with her ongoing academic background in economics, she analyzes earnings, digital market, and the commercial strategies powering the global tech sector.