

 LinkedIn
 MoneyHash Helps Luno Recover 25% of Lost Crypto Deposits
Nigeria's Grey Wins CBN License for Direct Inbound Funds
The Central Bank of Nigeria granted international money transfer operator approval to cross-border payments platform Grey, enabling direct inbound diaspora remittance processing into local bank accounts for millions of remote workers and international contractors.
Inioluwa Ademidun | · 7 min read
Sending money home to family members in Nigeria has spent decades trapped in bureaucratic banking corridors. When a software developer working remotely from Lagos receives payments from an American client, or when a healthcare worker in London sends funds home to elderly parents in Ibadan, transactions historically moved through layers of correspondent banks. Wire fees drained up to ten percent of the transfer value, while foreign exchange settlement delays forced recipients to wait days for funds to clear into domestic bank accounts. Informal street currency dealers stepped into that void, creating parallel market risks and depriving national reserves of foreign currency. Nigerian financial technology venture Grey dismantled those intermediary hurdles on Thursday, November 5, 2026. The company announced that it secured formal approval from the Central Bank of Nigeria to operate as an International Money Transfer Operator (IMTO). The regulatory license grants Grey the legal authority to handle inbound diaspora remittances directly, settling foreign currency transfers straight into Nigerian commercial banks and mobile wallets without relying on third-party intermediaries. The milestone arrives as diaspora capital flows reach record highs, continuing cross-border financial developments we tracked when Taja surpassed fifty thousand users across seven African markets.
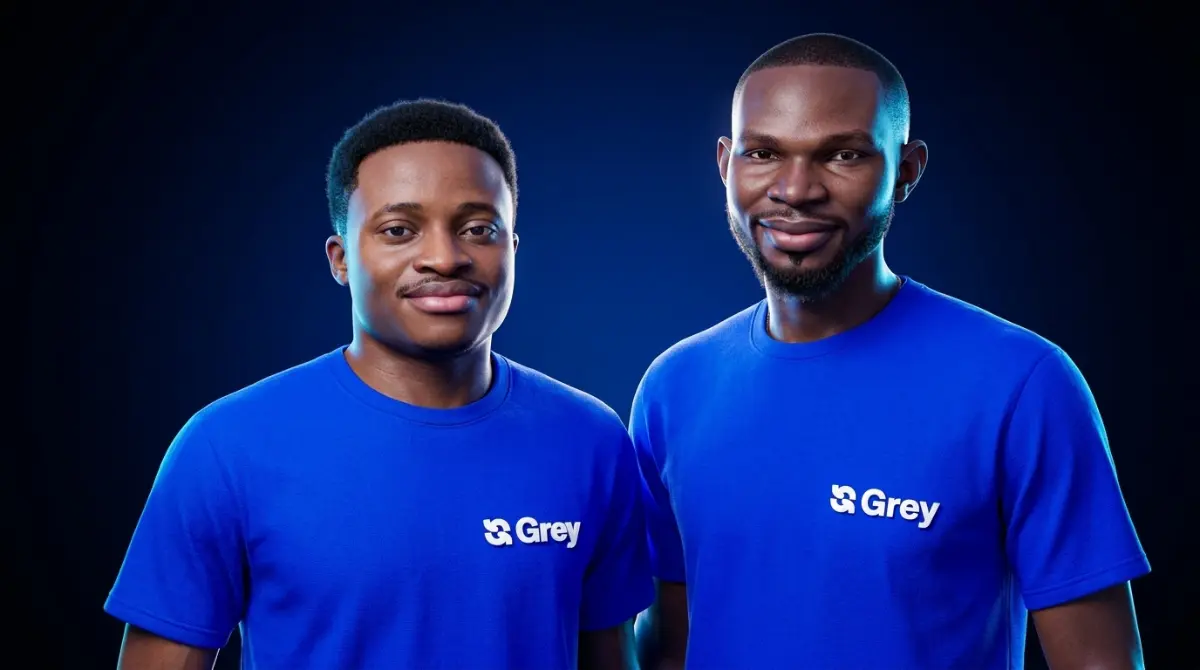
The regulatory approval marks an important corporate step for co-founder and Chief Executive Officer Idorenyin Obong and his executive team. Founded in 2020 to help African remote workers open foreign currency bank accounts, Grey expanded its footprint across Kenya, Ghana, Uganda, and the United Kingdom, serving over five hundred thousand registered accounts. Previously, when a Grey user in Nigeria converted foreign currency earnings into naira, the transaction had to clear through licensed third-party commercial bank partners, adding processing latency and compliance friction. With a direct IMTO license, Grey connects directly to the Central Bank of Nigeria foreign exchange clearing gateway. Transfers from London, Toronto, or New York arrive in domestic Nigerian bank accounts in seconds at official interbank exchange rates. The timing is opportune: World Bank records show that personal remittance inflows into Nigeria totaled $22.8B in 2025, representing an essential source of foreign currency liquidity for the national economy. The direct licensing push reflects broader regulatory reorganizations across African fintech, matching developments we monitored when South Africa opened national payment rails to non-bank fintech companies.
The Diaspora Remittance Engine: Twenty-Two Billion Dollars Annually
To grasp why an IMTO license carries immense commercial value, one must inspect the macroeconomic importance of remittances across sub-Saharan Africa. Remittance flows sent home by the Nigerian diaspora exceed the foreign direct investment and crude oil earnings retained by the national treasury.
Millions of Nigerian professionals living abroad in the United Kingdom, the United States, Canada, and Europe send monthly allowances to support relatives with university tuition, medical expenses, and housing construction. At the same time, Nigeria educated youth population has embraced remote digital work: working as software engineers, graphic designers, technical writers, and customer support specialists for international technology companies. These remote workers earn in United States dollars, British pounds, or euros, needing reliable digital rails to convert their earnings into naira for daily living expenses. In the past, high bank fees and poor exchange rates pushed transactions toward unregulated informal peer-to-peer channels. By granting IMTO licenses to agile technology platforms like Grey, the Central Bank of Nigeria aims to bring these capital flows into transparent, regulated banking channels, stabilizing the national currency and boosting official foreign exchange reserves. Financial inclusion and localized payment rails were detailed in our analysis of Central Bank of Nigeria payment rules targeting market concentration.
Direct Settlement vs. Intermediary Routing: The Speed Advantage
The operational breakthrough delivered by the IMTO license sits in payment routing architecture. Operating without an IMTO license forced fintech startups to act as secondary middlemen, routing customer funds through local commercial banks that held regulatory permissions.
This intermediary structure introduced points of failure:
- Excess Processing Fees: Commercial bank partners charged intermediary routing fees, forcing fintech apps to pass costs onto consumers through wider exchange rate spreads.
- Settlement Delays: If an intermediary bank experienced nighttime server maintenance or holiday backlogs, customer transfers sat pending for hours.
- Regulatory Counterparty Risk: If a partner commercial bank faced central bank audits or operational restrictions, fintech customer deposits were frozen collateral damage.
Holding a direct IMTO license eliminates the banking middleman. Grey connects directly to the Nigeria Inter-Bank Settlement System (NIBSS) and central clearing switches. When an expatriate worker in Manchester initiates a £200 transfer through the Grey mobile app, the system converts the currency using real-time interbank rates and deposits naira into a recipient account at Zenith Bank or GTBank within five seconds. Direct settlement cuts transaction fees by more than half, providing users with transparent pricing. Enterprise payment orchestration across African markets matches models we examined when MoneyHash helped Luno recover twenty-five percent of lost deposits.
Comparing Cross-Border Remittance Platforms Serving Nigeria
| Platform Operator | Regulatory Authorization | Primary Target User | Foreign Account Issuance | Average Transfer Settlement Speed |
|---|---|---|---|---|
| Grey (Paycheck Inc) | Direct CBN IMTO License | Remote workers & diaspora families | USD, GBP, EUR virtual IBANs | Under 10 seconds via direct rails |
| LemFi (RightCard) | Direct CBN IMTO License | UK/US diaspora immigrant families | Multi-currency diaspora wallets | Instant bank deposit routing |
| Flutterwave | Direct CBN IMTO License | Enterprise merchants & Send app | Virtual business accounts | Real-time via enterprise rails |
| Western Union / MoneyGram | Traditional licensed legacy IMTO | Cash pickup & physical retail | Zero virtual account capability | Minutes to hours (High fees) |
| Chipper Cash | Regional partner bank routing | Peer-to-peer consumer transfers | USD virtual cards | Variable based on bank partner uptime |
The comparative data illustrates how Grey positioned itself in the competitive financial corridor. While legacy operators like Western Union charge high transaction commissions for physical cash pickups, Grey combines direct central bank licensing with virtual bank accounts. A remote software engineer in Abuja can share their personal European IBAN account details with an employer in Berlin, receive direct SEPA payroll deposits, and convert funds into domestic naira on their phone without paying international wire surcharges. Pan-African digital payment expansion matches trends we reviewed when Airtel Money posted strong revenue gains across regional markets.
Compliance and Anti-Money Laundering Frameworks
Securing an IMTO license from the Central Bank of Nigeria requires satisfying rigorous regulatory compliance audits. In past years, central bank authorities were wary of digital fintech platforms, concerned that automated transfer apps could facilitate capital flight or violate currency controls.
Grey satisfied regulatory scrutiny by upgrading its compliance architecture. The platform deployed real-time identity verification linked to national identity registries: validating Nigerian Bank Verification Numbers (BVN) and National Identification Numbers (NIN) alongside British and European passport databases. Automated transaction monitoring algorithms inspect transaction patterns, flagging unusual volume spikes, rapid account velocity, or transfers connected to sanctioned entities before funds enter domestic clearing systems. By demonstrating strict anti-money laundering and counter-terrorist financing controls, Grey proved to regulators that digital fintech platforms can enhance financial transparency rather than compromising it. Regulatory compliance and licensing standards were detailed in our analysis of Airtel Money implementing anti-money laundering frameworks.
The Road Forward for African Cross-Border Commerce
The granting of an IMTO license to Grey marks an important victory for Nigerian financial innovation. For decades, international finance treated African cross-border transactions as high-risk, low-priority corridors that justified exorbitant fees and sluggish service.
A new generation of African founders has proven that modern software plumbing can deliver fast, transparent, and compliant cross-border finance. As Grey deploys its direct clearing rails, Idorenyin Obong and his team are connecting millions of talented African workers directly to the global economy. The road ahead will require expanding foreign banking partnerships across North America and Asia, managing foreign exchange liquidity pools, and defending digital perimeters from cyber fraud. Grey regulatory milestone proves that the future of African commerce will not be shaped by legacy banking monopolies, but by agile technology platforms that tear down financial borders, allowing human talent and capital to flow freely across the world.
Read More on TechRobust:
Inioluwa Ademidun
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.
Related Stories
MoneyHash Helps Luno Recover 25% of Lost Crypto Deposits PhiDoc Launches Research Platform for African Scholars
 DPI Closes $112M Nclude Fund for African Startups