

 LinkedIn
 Nigeria's Grey Wins CBN License for Direct Inbound Funds
Raenest Buys UK Firm Remitise to Expand British Rails
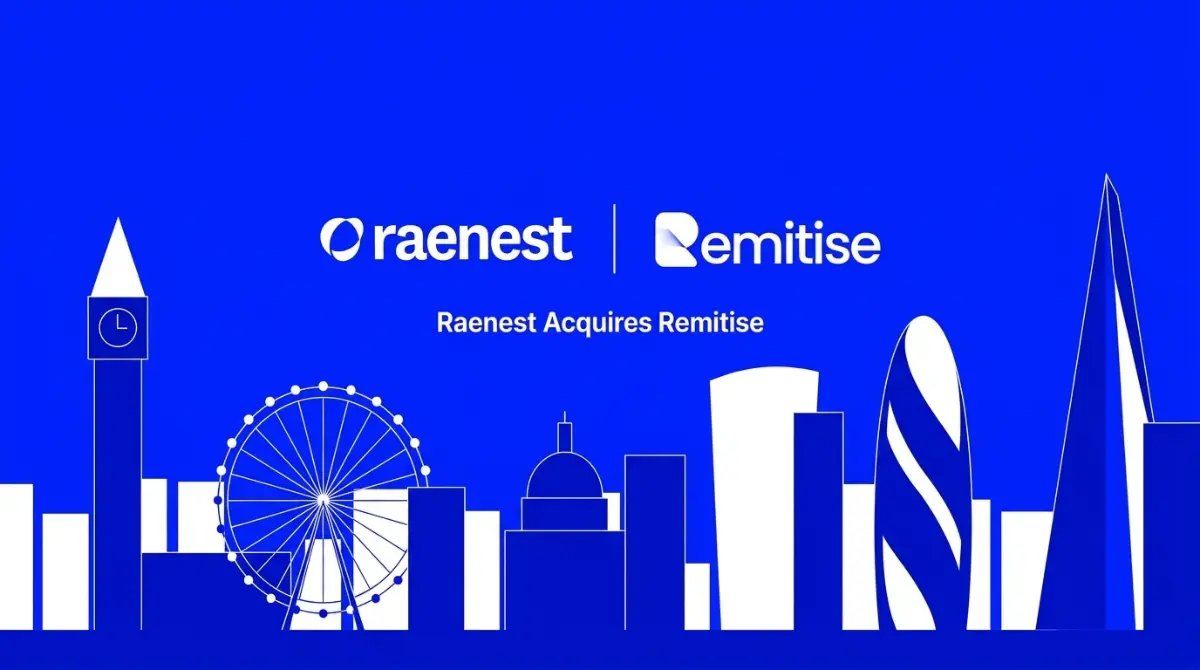
Nigerian cross-border payments platform Raenest completed the outright acquisition of British payments firm Remitise, securing a direct Financial Conduct Authority regulatory license in London to accelerate foreign currency transfers for remote African contractors and international businesses.
Inioluwa Ademidun | · 9 min read
African technology companies spent a generation watching Western payment giants enter their home markets to buy up local payment gateways. European and American financial institutions treated emerging market fintechs as downstream distributors, collecting interchange fees while keeping primary clearing rails in London and New York. That historical flow of capital reversed course on Tuesday, November 10, 2026. Nigerian cross-border financial platform Raenest confirmed the outright acquisition of Remitise Limited, a payments company registered in the United Kingdom with the Financial Conduct Authority. The transaction hands Raenest one hundred percent ownership of the London-based entity, providing the African fintech with an authorized corporate vehicle in Western Europe. By buying an established payments business rather than spending years waiting in administrative regulatory queues, Raenest bypasses the third-party intermediary networks that inflate wire costs for African remote workers. The acquisition arrives as cross-border settlement rails face regulatory resets worldwide, continuing financial infrastructure expansions we monitored when Taja surpassed fifty thousand users across seven African markets.
The cross-border buyout marks a milestone for co-founders Victor Alade, Richard Oyome, and Sodruldeen Mustapha. Founded in 2022 to help African freelancers collect dollar payments from international marketplaces like Upwork and Fiverr, Raenest grew into a global accounts platform serving over 1.5 million registered customers. Lifetime processed volume recently crossed $3B, backed by an $11M Series A funding round completed in early 2025 under the lead of QED Investors. Alade explained that acquiring Remitise is another step toward building a reliable global financial platform. He stated that the purchase helps the company better serve existing accounts today while supporting their commercial needs as they scale internationally. Financial details of the transaction were kept private, but the strategic prize is undeniable: acquiring an active registration under UK Financial Conduct Authority payment regulations allows Raenest to anchor British pound settlements directly. The cross-border acquisition lands as central banks update licensing standards, matching supervisory shifts we examined when the Central Bank of Nigeria payment rules targeted market concentration.
The BaaS Breakdown: Why Owning the License Matters
To inspect why an African fintech decided to purchase a British payments firm, one must examine the fragility of Banking-as-a-Service partnerships. For years, cross-border startups launched by renting regulatory permissions from sponsor banks and licensed middleman brokers.
That rented model collapsed across Western markets over the past two years. High-profile compliance failures, balance sheet freezes at middleware platforms, and strict enforcement orders from American and British regulators left dozens of consumer fintech apps stranded overnight. When a sponsor institution faces regulatory audits or changes its internal risk tolerance, partner accounts are frozen without warning. African fintech founders discovered that relying on third-party Western sponsors placed their businesses in constant danger. By acquiring Remitise, Raenest shifts from being a client of Western financial plumbing to owning the regulatory asset directly. Remitise operates as a Small Payment Institution under British regulations (FCA Reference 931409), granting it legal authority to execute payment transactions, manage money remittances, and operate payment accounts within statutory thresholds. Owning the registered entity eliminates middleman fees, reduces transfer failure rates, and gives Raenest direct standing to negotiate clearing accounts with Tier 1 British commercial banks. The retreat from fragile partner sponsorship mirrors corporate strategies we followed when Luno acquired Kenyan fintech GTXN to build cross-border rails.
The London to Lagos Corridor: The Economics of Human Mobility
The geographic focus of the transaction connects directly to migration and international employment. The economic corridor linking the United Kingdom with Nigeria represents one of the fastest-growing remittance routes in global trade.
Official records tracked by World Bank remittance tracking data demonstrate that annual diaspora inflows into Nigeria consistently exceed $20B. Over the past five years, hundreds of thousands of Nigerian nurses, doctors, software engineers, and university students relocated to British metropolitan centers including London, Manchester, and Birmingham. These individuals maintain close ties with relatives back home, sending monthly allowances for healthcare, family businesses, and housing construction. Concurrently, thousands of Nigerian professionals remain based in Lagos and Abuja, working remotely as contractors for British and European employers. Receiving paychecks in British pounds historically required waiting days for international SWIFT wires to clear through correspondent banks, with intermediary fees deducting up to seven percent of the paycheck value. Raenest provides remote workers with virtual UK accounts complete with individual sort codes and account numbers. When a British client sends funds via local Faster Payments rails, the money lands in the contractor balance in seconds. The contractor can hold the pounds, convert them into naira at market rates, or spend them globally using virtual cards. Commercial card issuance across borders was detailed in our report on Comparing Cross-Border Expansion Models for African Fintechs
The comparative data illustrates how regulatory ownership has become the definitive competitive divide. Early consumer money apps relied on white-label banking rails, which left them vulnerable to fee hikes by sponsor institutions. Raenest joins a select cohort of African operators that hold registered entities across multiple continents. By combining an FCA registration in London with an International Money Transfer Operator licence from the Central Bank of Nigeria financial regulations and Money Services Business registrations in Canada, Raenest controls both ends of the transaction conduit. When a customer moves money from London to Lagos, Raenest acts as the originating sender in the United Kingdom and the settling entity in Nigeria, cutting out third-party fees. Licensing expansion across international borders matches patterns we tracked when Revolut secured banking licenses in emerging markets. The acquisition of Remitise mirrors the evolution of Raenest corporate business model. When Victor Alade, Richard Oyome, and Sodruldeen Mustapha launched the venture four years ago, the value proposition was simple: helping local programmers cash out Upwork balances without losing twenty percent to street currency exchangers. That initial retail feature revealed a much larger commercial opportunity: African startups and mid-sized enterprises needed international banking rails. An enterprise software firm based in Nairobi or Cairo frequently employs workers across five countries, sells services to European corporate buyers, and pays monthly software invoices to cloud platforms. Traditional African commercial banks make foreign trade difficult: enforcing strict foreign exchange limits, requiring physical paper documentation for wire transfers, and delaying vendor settlements by weeks. Raenest expanded beyond retail freelancers to build Raenest for Business: providing corporate accounts, automated contractor payroll runs, multi-currency corporate debit cards, and stablecoin settlement options. Today, over eleven thousand businesses use Raenest to manage cross-border operational capital. Owning Remitise allows Raenest to offer British pound accounts to international corporate clients with increased regulatory certainty. Enterprise treasury management across high-growth markets was explored in our analysis of Airtel Money posting strong revenue gains across regional markets. Executing cross-border corporate buyouts requires balance sheet strength and investor backing. In February 2025, Raenest secured $11M in a Series A equity round led by QED Investors, the premier financial technology venture firm founded by Nigel Morris. QED investment was an explicit endorsement of Raenest infrastructure-first strategy. Total funding raised by the startup crossed $14M, giving the company dry powder while competing regional startups struggled through a venture funding drought. While many early-stage fintechs burnt cash on consumer marketing campaigns and billboard advertisements, Raenest directed capital toward compliance and regulatory licensing. Securing licenses in Canada, Nigeria, and now the United Kingdom gives the business a durable competitive moat. Venture capital deployment into sustainable African platforms matches institutional investment trends we monitored when Ventures Platform closed an institutional venture fund. While acquiring Remitise is a major commercial victory, regulatory analysts note that operating as an FCA Small Payment Institution carries clear statutory limitations. Under British financial regulations, an SPI registration is designed for small to mid-sized payment providers. FCA guidelines restrict an SPI from executing average monthly payment transactions exceeding €3M (approximately £2.5M). If transaction volume on the Remitise rail consistently surpasses that regulatory ceiling, Raenest must apply to upgrade its status to an Authorised Payment Institution (API). Becoming a fully Authorised Payment Institution requires higher capital reserves, deeper operational audits, and expanded compliance reporting to British authorities. Raenest has not yet set a public timeline for when it plans to transition Remitise from an SPI to a full API, but its current $3B lifetime volume proves that the company will quickly approach statutory volume caps. The acquisition serves as a working bridgehead: giving Raenest an active, compliant corporate footprint in London that can be upgraded as transaction volume grows. Opening payment rails to non-bank fintechs matches market reforms we analyzed when South Africa opened national payment rails to non-banks. The broader historical significance of Raenest buying Remitise touches the shifting power dynamics of global technology finance. For decades, international finance followed an extraction pattern: Western institutions controlled the settlement rails, dictate terms, and took the profits, while African businesses remained dependent users. A generation of African founders who built platforms in high-inflation, complex regulatory environments is now expanding outward. Managing liquidity across volatile currency environments like the Nigerian naira or Ghanaian cedi forces founders to master risk management and capital allocation early in their corporate lives. When those same founders enter mature Western markets like the United Kingdom, they operate with operational resilience and speed that legacy European institutions struggle to match. Raenest purchase of Remitise proves that African fintech is no longer confined to regional survival; it is building global financial rails that compete on the world stage. As trade between Africa, Europe, and North America expands, the institutions that facilitate cross-border exchange will not be defined by where their founders were born, but by the speed, transparency, and reliability of the rails they construct for the modern world. Read More on TechRobust:
Fintech Platform
Primary UK Regulatory Route
African Domestic Anchors
North American Licences
Primary Target Demographic
Raenest
Direct acquisition (Remitise FCA SPI)
Nigeria CBN IMTO licence
Canada FINTRAC MSB & PSP
Remote contractors & global startups
LemFi (RightCard)
Direct FCA Authorised Payment Inst.
Nigeria CBN IMTO approval
Canada MSB registration
Immigrant diaspora family remittances
Grey (Paycheck Inc)
Third-party banking rail partnerships
Direct CBN IMTO licence
US / UK partner banking links
Digital nomads & tech freelancers
Flutterwave
UK commercial branch partnerships
Commercial switching licences
State-by-state US money licenses
Enterprise merchants & corporate trade
Chipper Cash
FCA authorized intermediary status
Multiple African domestic pacts
US money transmission network
Peer-to-peer social transfers
From Upwork Payouts to Corporate Global Treasury
The QED Backing: Institutional Capital Behind the Expansion
The Small Payment Institution Limits: The Road to Full Authorization
The Reverse Scramble: Emerging Market Founders Buying Western Rails
Inioluwa Ademidun
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.
Related Stories
Nigeria's Grey Wins CBN License for Direct Inbound Funds MoneyHash Helps Luno Recover 25% of Lost Crypto Deposits
 PhiDoc Launches Research Platform for African Scholars