

Apollo Warns Enterprise AI Yields Zero Real Payoff
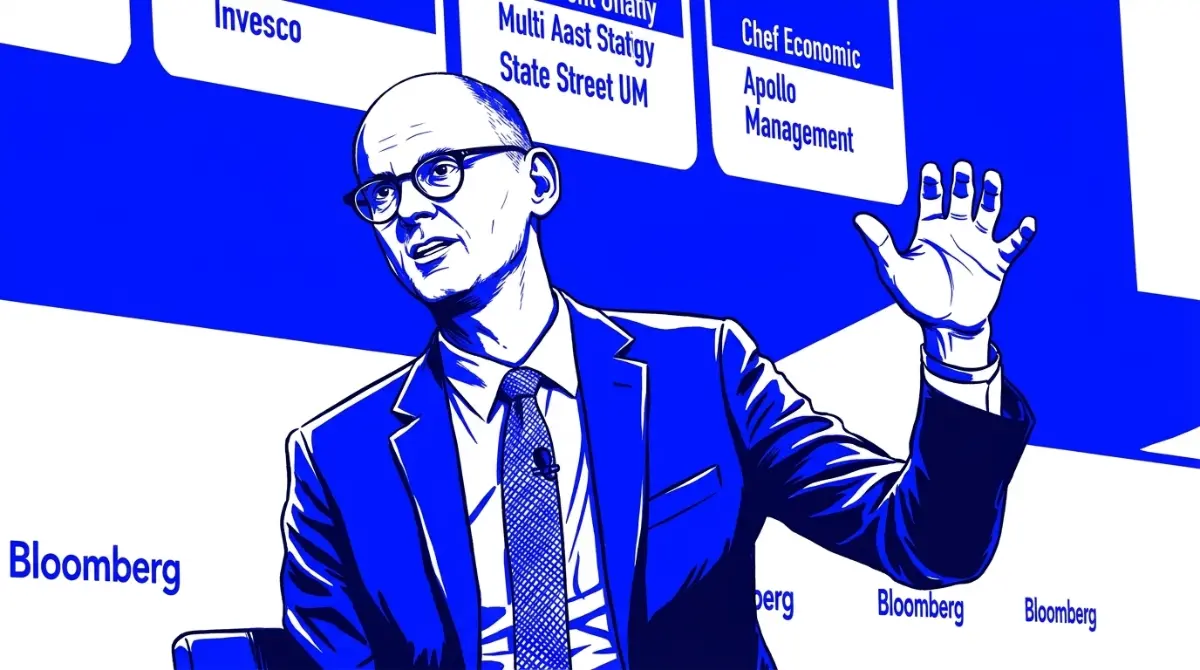
Apollo Global Management chief economist Torsten Slok warned that enterprise investments in automated systems yield zero measurable financial return for most corporations, predicting that mounting software depreciation and unfulfilled productivity promises will trigger a sharp corporate spending retreat.
Umar Thariwat | · 6 min read
Corporate balance sheets are carrying billions in speculative software expenses with nothing to show on income statements. Chief financial officers approved massive software licensing agreements, rented graphics processor clusters, and paid consultants six-figure retainers to install automated pilots across accounting, marketing, and human resources. Executive suites promised public shareholders that machine intelligence would expand profit margins and reduce structural payrolls. The actual financial return has failed to appear. Torsten Slok, chief economist at private equity giant Apollo Global Management, published a research assessment warning that artificial intelligence investments deliver zero measurable financial payoff to the vast majority of corporations. Slok noted that while hardware manufacturers and cloud hosts book historic revenues selling computing equipment, non-technology enterprises adopting these tools see zero acceleration in revenue growth or net earnings. The economic warning lands as public equity markets re-evaluate technology valuations, continuing corporate financial scrutiny we documented when Wall Street set impossible profit targets on tech earnings.
The critique from Apollo strikes at the center of modern capital allocation. Over the past three years, corporate leaders justified rising operating budgets by claiming that early software adoption was mandatory for survival. Enterprise surveys show that while ninety percent of Fortune 500 corporations launched machine learning pilots, fewer than five percent deployed applications that produced verifiable cost reductions or incremental sales. Slok observed that the corporate software boom behaves like a classic capital expenditure bubble: money circulates among semiconductor producers, server assemblers, and cloud facilities, but stops dead when reaching traditional commercial businesses. Everyday corporations end up paying monthly subscription fees for conversational wrappers that employees use for drafting casual emails and summarizing internal meetings. Slok warned that when chief executive officers realize these tools fail to move profit needles, enterprise software budgets will face severe cancellations. Macroeconomic warnings regarding heavy capital concentration were explored in our analysis of economists warning of systemic risks from capital spending.
The Productivity Paradox of Office Automation
To evaluate Slok assessment, one must inspect how white-collar enterprises measure operational output. In manufacturing plants, technological return is simple to track: installing an automated welding station increases finished automobile frames per shift while lowering scrap rates. In office environments, measuring cognitive output remains notoriously difficult.
Enterprise software vendors promised that automated document processing would allow corporations to complete assignments with fewer employees. What corporate managers discovered is that conversational assistants frequently create make-work. An employee who previously spent twenty minutes writing a project memo now spends five minutes generating a three-page draft with software, followed by fifteen minutes editing errors, verifying facts, and reformatting text. The net time saved is negligible. Furthermore, when workers produce longer memos and reports with automated tools, colleagues must spend additional hours reading and responding to that text. Instead of shrinking administrative work, corporate offices find themselves drowning in synthetic documentation. Corporate labor shifts following technology adoption match patterns we followed when corporate technology deployments replaced thousands of administrative hours.
The Hardware Depreciation Trap for Enterprise Adopters
The financial hazard highlighted by Apollo centers on corporate accounting rules. When an enterprise purchases computing servers or commits to multi-year cloud infrastructure leases, accounting standards mandate that those capital outlays be expensed over fixed depreciation cycles.
High-end server processors and accelerator dies carry rapid depreciation cycles of three to five years, because newer chip generations render older architectures uneconomical to operate. An enterprise that spent $50M establishing internal server facilities must absorb $10M to $12M in annual non-cash depreciation charges against operating income. If the automated tools running on those servers do not generate at least $15M in new net revenue or verified payroll reductions, the investment reduces net margins. Slok explained that mid-market corporations are realizing that software pilots represent net cash drains. As board directors review 2027 capital expenditure budgets, projects lacking clear financial paybacks will face termination. Infrastructure strains across enterprise facilities were analyzed in our report detailing how America computing infrastructure expansion began to stall.
Comparing Enterprise Technology Transitions
| Technology Wave | Primary Capital Driver | Typical Time to Net ROI | Measurable Productivity Lift | Enterprise Adoption Risk |
|---|---|---|---|---|
| Enterprise AI Tools (2024 to 2026) | Cloud GPUs, foundation models, coding bots | Unrealized (Zero payoff for majority) | Negligible in non-tech sectors | High depreciation fees & unverified gains |
| Cloud Migration (2010 to 2020) | Virtual servers, SaaS subscriptions, data lakes | 3 to 5 years | Lower on-site IT maintenance payrolls | Cloud vendor price inflation |
| Enterprise ERP (1995 to 2005) | Relational databases, SAP, supply chain software | 4 to 7 years | Unified inventory & faster billing cycles | Multi-million dollar installation overruns |
| Personal Computers (1982 to 1992) | Desktop microcomputers, spreadsheet tools | 5 to 8 years | Displaced typing pools & paper ledgers | Initial training delays & repair hurdles |
The comparative data illustrates that general-purpose technology transitions routinely require years before delivering measurable economic returns. In earlier computing eras, businesses had to reorganize business processes before computers produced profits. Apollo analysis suggests that modern enterprise software was sold as an immediate cure-all, creating unrealistic expectations that cannot survive balance sheet audits. Corporate efforts to automate financial operations were examined in our review of Ramp expanding autonomous financial systems.
The Spending Reckoning for Enterprise Software Vendors
The direct victims of an enterprise spending freeze will be software startups and cloud service platforms that priced subscription tiers on expectations of corporate expansion. Many software ventures secured rich private valuations by promising that corporate clients would expand seat licenses continuously.
If enterprise buyers determine that machine assistants do not improve revenue margins, IT departments will cancel seat licenses and downgrade premium tiers. Enterprise software procurement officers are shifting from open-ended experimentation to strict performance audits: demanding that software vendors prove return on investment before renewals clear. Software applications that simply repackage third-party model APIs without proprietary data connections will face high customer cancellations. Software providers will be forced to compete on price, compressing operating margins across the technology industry. Shifting investor sentiment across software venture capital was detailed in our coverage of software ventures acquiring smaller specialized teams.
The Future Outlook for Enterprise Computing Capital
Torsten Slok warning delivers a necessary dose of financial realism to an industry intoxicated by promotional demonstrations. Machine intelligence remains an impressive technological accomplishment, but technology alone does not guarantee commercial profits.
For an enterprise investment to generate real financial return, it must solve a concrete commercial problem: reducing production costs, opening fresh sales channels, or accelerating product delivery to paying customers. Software tools that merely automate casual workplace conversations fail that commercial test. As corporations enter 2027, chief executives and finance directors will demand verifiable numbers rather than marketing promises. The companies that succeed will not be those that spend fortunes on speculative computational clusters, but the disciplined operators who deploy software where it delivers measurable, compounding cash flows to the corporate bottom line.
Read More on TechRobust:
Umar Thariwat
 LinkedIn
Umar Thariwat
Expertise:Tech News Reporting, Tech Business Analysis, Economic Foundations, Market Trends, Digital Economy
Award:Rising Voice of the Year 2025
Thariwat is a Staff Writer and Reporter covering tech news and enterprise trends at TechRobust. Blending daily reporting with her ongoing academic background in economics, she analyzes earnings, digital market, and the commercial strategies powering the global tech sector.