

Wall Street AI Boom Faces Impossible Earnings Targets
Wall Street equity valuations pushed market concentration to record heights, leaving corporate analysts worried that Big Tech earnings cannot fulfill massive artificial intelligence expectations as server equipment depreciation and energy expenses mount across corporate ledgers worldwide.
Umar Thariwat | 12 Oct. 2026, 8:51 PM · 9 min read
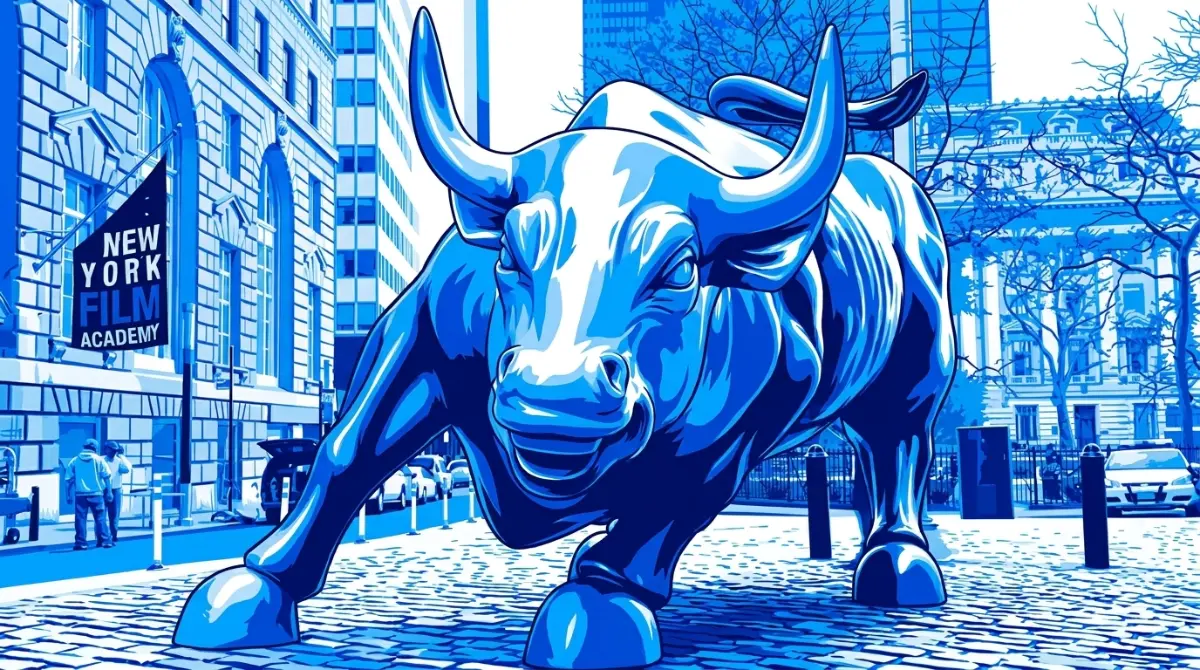
Public stock exchanges have tied their fortunes to a single technological wager. Over the past three years, equity indexes across the United States climbed to historic highs on the promise that synthetic reasoning would remake corporate productivity. Investors poured trillions into a small cluster of mega-cap technology corporations, treating computer infrastructure builders like invincible cash generators. That speculative momentum pushed market concentration past levels seen during the dot-com bubble or the gilded age of rail barons. On Monday, October 12, 2026, Reuters published an extensive financial commentary titled Open Interest, warning that the financial bar set for artificial intelligence has grown too high to hit. Market analysts noted that corporate valuations now demand unbroken double-digit revenue expansion from software products that remain costly to run and difficult to monetize. The warning arrives as macroeconomic institutions evaluate the industrial fallout of hardware spending, a subject detailed when the IMF confirmed that hardware spending supports global growth.
The core dilemma facing financial markets is mathematical rather than philosophical. When a handful of technology giants account for more than thirty percent of the entire standard equity index, any minor hesitation in corporate spending creates outsized shocks across retirement funds and sovereign portfolios. Investors spent twenty-four months rewarding corporate executives simply for mentioning computational clusters and server acquisitions on quarterly conference calls. Now, institutional fund managers are demanding real balance sheet receipts. Companies that pledged billions to build server halls must demonstrate that everyday enterprise clients are paying enough in software subscriptions to cover electricity, cooling, and silicon depreciation. If enterprise software receipts fail to match Wall Street targets, equity prices could face sharp downward revisions. The mounting capital costs tied to hardware expansion mirror issues we analyzed when Oracle delayed data center spending over power supply fights.
The Concentration Risk Inside Modern Stock Indexes
To grasp why Wall Street is nervous about corporate quarterly updates, one must look at how index weightings have warped. The broader stock market is no longer an accurate reflection of diverse industrial sectors like manufacturing, retail, logistics, and healthcare. It has become a leveraged bet on a small group of hardware designers, cloud providers, and software monopolies.
Nvidia, Microsoft, Apple, Alphabet, Amazon, and Meta collectively added trillions in equity valuation over a thirty-six-month window. This narrow concentration means that normal portfolio diversification has vanished for passive index fund investors. When pension managers purchase an index fund, they are overwhelmingly purchasing shares in server parks and graphics silicon. If software demand slows, or if enterprise buyers pause application rollouts to evaluate costs, the entire stock market drops in sympathy. Historical market records show that periods of extreme equity concentration rarely resolve smoothly; they usually culminate in volatile corrections that rebalance capital toward neglected market sectors. The systemic hazards of centralized capital flows were examined in our review of economists warning of systemic risks from capital spending.
Depreciation Schedules and the Server Wall
The financial pressure building inside Big Tech corporate ledgers centers on the brutal math of physical depreciation. In software businesses, code does not rot. A digital application written five years ago can continue generating high-margin subscription cash with minimal maintenance expenses. Hardware operates under entirely different accounting realities.
A high-performance computing server cabinet packed with liquid-cooled accelerators, high-speed memory modules, and specialized optical interconnects carries an immense upfront cost. Corporate accountants typically write off server hardware over a four-to-five-year period. This means that a cloud platform spending $40B on hardware this year must absorb roughly $8B to $10B in annual non-cash depreciation charges against operating earnings. If those servers do not generate immediate, high-margin software revenues, operating margins contract rapidly. Because chipmakers release faster, more power-efficient processor designs every eighteen months, older hardware loses commercial rental value before accountants finish writing off the original purchase price. The financial risks of managing physical server racks match challenges we followed when FTX mining assets entered the server facility buildout.
The Enterprise Return on Investment Gap
While technology providers boast about customer inquiries, enterprise software buyers are displaying corporate caution. Chief information officers across Fortune 500 banks, insurance firms, and retail conglomerates are conducting internal audits to measure the real financial return on automated software tools.
During the initial excitement, corporations signed enterprise pilot contracts to test conversational assistants, document extraction tools, and automated customer triage agents. Yet two years into production trials, corporate finance teams are discovering that deploying automated software at scale carries hidden costs. Systems require expensive data cleaning, continuous human verification queues, specialized prompt engineers, and heavy cloud computing fees. If an automated customer support platform saves $2M in human labor but generates $3M in monthly model query charges, the corporate investment destroys shareholder value. Enterprise executives are beginning to push back against vendor rate increases, refusing to renew software licenses unless vendors prove measurable labor savings. The reality of enterprise software adoption was evaluated in our report on corporate technology deployments freeing thousands of administrative work hours.
Energy Limits as an Unforgiving Valuation Cap
Even if customer demand remains robust, technology conglomerates face physical barriers that financial markets cannot solve through equity printing: electrical grid limits. Running modern computing centers requires uninterrupted, high-voltage electricity that regional power utilities were never constructed to supply.
Across major technology hubs in Northern Virginia, Central Texas, Ireland, and Germany, transmission operators have frozen fresh utility interconnections. A cloud provider can raise $10B in corporate bond markets in an afternoon, but it cannot force a municipal power board to deliver 500 megawatts of electricity out of thin air. Constructing modern high-voltage transmission lines, substations, and natural gas peaking facilities takes five to eight years of regulatory hearings and environmental reviews. When server facilities cannot secure power hookups, expensive computing processors sit inside wooden crates rather than processing paid customer traffic. Wall Street earnings projections assume unbroken computational expansion, yet physical grid limits threaten to cap actual revenue growth. The escalating friction between utilities and server operators was documented when water and power constraints threatened multi-billion dollar server campuses.
The Circular Revenue Flow Among Tech Monopolies
Another issue troubling institutional asset managers is the circular structure of current technology revenue. A sizeable portion of the financial growth reported by hardware makers does not originate from end-user consumers or traditional non-tech enterprises; it flows from other technology companies and venture-backed research laboratories.
Cloud platform giants invest billions into foundation model startups, and those startups immediately hand that cash back to the cloud platforms to pay for server compute time. Hardware makers take equity stakes in cloud hosting providers, who then turn around and buy massive purchase orders of graphics chips. This internal cash recycling creates an illusion of widespread commercial demand. If venture capital funding for early-stage software startups dries up, or if private foundation laboratories face liquidity crunches, the circular purchasing loop stops abruptly. When external revenue from ordinary businesses fails to replace venture subsidies, headline revenue figures for hardware makers could experience sharp drops. The venture dynamics driving these circular investments were detailed when Crusoe secured $3B to expand physical computing hubs.
The Threat of Cheaper Open-Weight Software
Proprietary software margins are also facing pressure from the rapid rise of open-weight alternatives. In 2023, technology analysts projected that two or three Western research firms would establish software monopolies, charging steep monthly subscription fees for access to closed reasoning models.
That closed commercial pricing model is collapsing. Research laboratories in Asia, Europe, and open-source communities are releasing capable open-weight models that perform complex coding and text reasoning at a fraction of closed commercial prices. When an enterprise can download an open-weight model, run it on private servers, and avoid paying recurring per-token fees to proprietary vendors, commercial software pricing power evaporates. Western cloud platforms are being forced into a brutal price war, cutting API token charges by up to 90% to defend developer market share. Squeezed software margins make it even harder for tech giants to earn back their massive infrastructure outlays. The competitive price pressure across digital models was examined in our analysis of leading cloud providers slashing model prices.
Public Sentiment and the Climate Pushback
Beyond financial calculations, the technology sector is confronting mounting social and political pushback. In communities located near large server campuses, local homeowners are organizing against industrial computing facilities, citing soaring municipal electric bills, noisy outdoor cooling towers, and depleted community water reservoirs.
State lawmakers across the United States are introducing legislation to eliminate tax breaks for data centers, demanding that technology giants fund their own dedicated clean power generation plants. If local governments impose utility surcharges or restrict water usage for server cooling, operating expenses for server parks will climb even higher. Institutional investors with environmental, social, and governance mandates are beginning to ask whether funding massive server campuses conflicts with their public net-zero commitments. The growing public anger surrounding computing power consumption was explored in our report on growing public pushback against server facility electrical consumption.
The Reallocation of Global Capital
The warning published by Reuters Open Interest reflects an important shift in market psychology. The era of unconditional market optimism, where any announcement containing the words machine learning sparked an immediate five percent jump in stock prices, is coming to an end. Financial markets are transitioning into an era of strict accountability.
Investors are beginning to reallocate capital toward traditional market sectors that trade at reasonable price-to-earnings multiples and generate reliable cash dividends. Energy producers, electrical equipment fabricators, civil engineering firms, and industrial manufacturers are attracting funds from investors seeking shelter from speculative technology stocks. The companies that supply the physical concrete, copper wiring, and power transformers required to build computing centers are often generating more dependable profits than the software firms leasing the servers. The rise of industrial computing suppliers was analyzed in our review of Marvell raising its revenue outlook on custom silicon demand.
The Inevitable Valuation Reckoning
Wall Street bet on artificial intelligence is not fundamentally misguided; the underlying technology represents a genuine leap in industrial automation and computing capability. The error lies in the compressed financial timeline demanded by equity markets. Building a global computational infrastructure, rewiring enterprise business workflows, and solving power grid constraints takes decades, not quarters.
When stock prices reflect twenty years of projected productivity gains compressed into a two-year valuation window, disappointment is unavoidable. If Big Tech earnings reports over the coming quarters reveal that revenue growth is slowing while capital expenses continue accelerating, markets will experience a necessary reset. The companies that survive that valuation correction will be those with durable balance sheets, disciplined capital allocation, and practical products that solve real human problems without burning fortunes in unmonetized electricity. The corporate stakes of this spending race were also evaluated in our coverage of Meta expanding its infrastructure budget beyond traditional limits, alongside custom silicon maneuvers tracked when Nuvacore targeted a $2.5B valuation for data center CPUs.
Read More on TechRobust:
Umar Thariwat
 LinkedIn
Umar Thariwat
Expertise:Tech News Reporting, Tech Business Analysis, Economic Foundations, Market Trends, Digital Economy
Award:Rising Voice of the Year 2025
Thariwat is a Staff Writer and Reporter covering tech news and enterprise trends at TechRobust. Blending daily reporting with her ongoing academic background in economics, she analyzes earnings, digital market, and the commercial strategies powering the global tech sector.