

Bumble to Go Private in $1.3B Ithaca Holdings Buyout
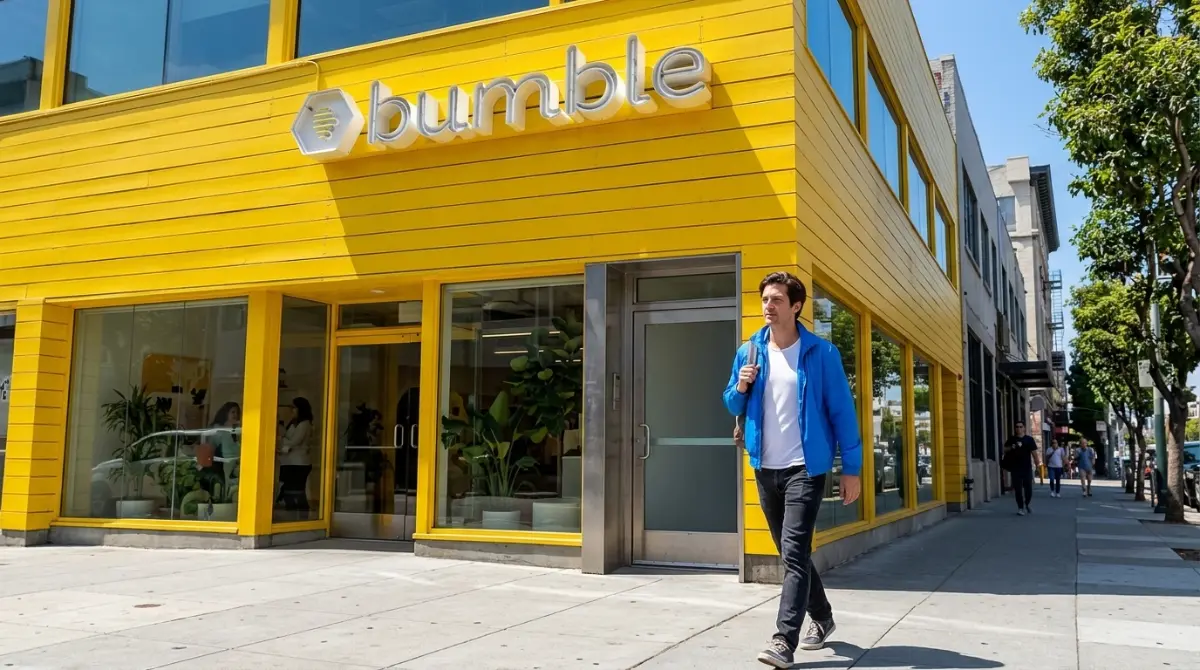
Dating platform Bumble agreed to an all-cash $1.3B buyout by Ithaca Holdings, taking the company private at $6.05 per share as founder Whitney Wolfe Herd prepares an overhaul to replace swiping mechanics amid subscriber fatigue.
Umar Thariwat | 13 Oct. 2026, 10:25 AM · 8 min read
Public stock markets have little patience for consumer applications that run out of growth momentum. When a mobile platform loses the attention of younger demographics, quarterly earnings calls turn into brutal valuation adjustments where public shareholders punish missing subscription numbers. Dating application pioneer Bumble discovered that market reality after years of falling engagement. On Tuesday, October 13, 2026, the Austin-based consumer technology enterprise announced an agreement to be acquired by private investment vehicle Ithaca Holdings. The all-cash transaction values Bumble at approximately $1.3B, paying stockholders $6.05 per share. The buyout marks an extraordinary decline for a consumer brand that captured international attention during its February 2021 market debut, when enthusiastic investors priced the company near $14B. The decision to exit public exchanges illustrates how consumer software companies seek shelter in private hands to execute deep product pivots, a corporate path we followed when Bending Spoons acquired Miro after a steep valuation drop.
The transaction is led by Ithaca Holdings, an investment vehicle directed by former Sequoia Capital partner Ravi Gupta. Under the terms of the agreement, founder Whitney Wolfe Herd will remain in her executive leadership post, working alongside Gupta to rebuild the application away from the scrutiny of Wall Street analysts. The buyout follows consecutive quarters of deteriorating operational numbers. In the second quarter of 2026, corporate revenue dropped 15.2% year over year to $211M, while paying subscriber numbers plummeted 16.4% to roughly 3.2M accounts. Young mobile users, exhausted by gamified matching queues and costly subscription tiers, have abandoned traditional dating apps in favor of offline social gatherings and niche messaging groups. Corporate consolidation across consumer software matches broader investment movements we documented when software ventures engaged in an aggressive corporate merger wave.
The Rise and Fall of the Feminist Dating Twist
To understand how Bumble lost more than ninety percent of its equity value in five years, one must examine the original market premise that made the app famous. Wolfe Herd co-founded the platform in 2014 after an acrimonious departure from Tinder, introducing a single structural rule: when heterosexual matches occurred, only women could initiate the conversation within a twenty-four-hour countdown window. That simple design choice gave women a sense of safety and control, distinguishing Bumble from the chaotic, unsolicited messages that plagued competing platforms.
The company expanded rapidly, attracting millions of college students and young professionals who appreciated the moderated atmosphere. When Bumble listed its shares on the Nasdaq in early 2021, Wolfe Herd became the youngest female founder to take an American company public, celebrated on magazine covers as an icon of modern consumer technology. Yet that core twenty-four-hour rule eventually turned into an operational barrier. Female users complained about feeling pressured to compose witty opening messages to dozens of matches every week, while male users grew frustrated watching promising matches expire without a word. What was once an empowering product feature had devolved into another digital chore, accelerating user churn across major metropolitan regions.
The Reality of Swipe Fatigue Across Generation Z
The deeper structural crisis facing Bumble is not unique to its corporate brand; it reflects an existential crisis for the entire swipe-based dating industry. For a decade, dating conglomerates like Match Group, which controls Tinder and Hinge, treated human romance like an endless arcade game. Users swiped through hundreds of digital profiles each evening, conditioning brains to view potential partners as disposable digital trading cards.
Younger adults belonging to Generation Z are rejecting that transactional format. College students report severe swipe fatigue, noting that spending hours tapping smartphone screens rarely leads to meaningful offline relationships. Instead of paying $25 a month for premium algorithmic boosts, young adults are turning to local run clubs, communal cooking classes, and group interest chats organized over WhatsApp and Discord. The monetization playbook of charging lonely users for basic visibility features has produced deep consumer cynicism, causing conversion rates to collapse across the sector. Consumer alienation with automated social software mirrors public sentiment we explored in our analysis of why users distrust automated software yet continue adopting it.
Ravi Gupta and the Private Capital Playbook
The entry of Ravi Gupta and Ithaca Holdings signals a calculated private equity strategy. Gupta built a reputation at Sequoia Capital by analyzing unit economics and operational discipline across consumer and enterprise businesses. Taking Bumble private removes the company from the quarterly earnings treadmill, where every dip in monthly active users triggers a selloff in company stock.
In a private environment, management can make painful, radical product changes that would panic public stock investors. Wolfe Herd has signaled plans to abandon the classic swipe interface entirely, experimenting with conversational matchmaking systems, shared real-world event coordination, and verified social circles. Private ownership allows the company to absorb two years of flat or negative revenue growth while rewriting the software codebase. If Ithaca Holdings can stabilize the user base and rebuild customer trust, the firm could return Bumble to public markets years later at a multiple of its $1.3B purchase price. The strategic maneuvers of private technology capital reflect patterns we tracked when regulators monitored private startup transactions and ownership records.
The Unproven Promise of Algorithmic Matchmaking
To revive user engagement, both Bumble and Match Group are betting heavily on automated algorithmic concierges. The theory being pitched by product designers is that software models will act as intelligent matchmakers: analyzing personal values, reading conversational pacing, and arranging dates between individuals with genuine compatibility, eliminating the exhausting process of endless manual profile browsing.
However, adding generative features to declining dating platforms has yet to produce measurable revenue turnarounds. Bumble launched Plans, a feature designed to help users coordinate real-world group outings, yet the tool failed to stop subscriber defections. Consumers remain skeptical of machine-directed romance, worried that dating platforms will use automated tools to extract higher subscription fees rather than helping them find lasting love. An algorithm that successfully pairs users into permanent relationships destroys its own recurring revenue stream; dating businesses depend on keeping single users searching on the platform. The tension between automated software convenience and authentic human relationships was evaluated in our report on tech leaders warning that automated communication erodes authentic relationships.
The Competitive Pressure From Match Group
While Bumble attempts its private restructuring, rival Match Group continues applying competitive pressure across consumer channels. Match Group shifted its marketing resources toward Hinge, positioning the app as designed to be deleted and capturing young professionals who abandoned Bumble. Hinge relationship-oriented branding allowed it to grow revenue while Bumble struggled with declining paying users.
Bumble attempt to diversify into professional networking through Bumble Bizz and platonic friendships via Bumble BFF also produced disappointing commercial returns. Neither secondary vertical developed into a significant revenue driver, leaving the corporate parent reliant on its core dating product. As an independent private company, Bumble will have to defend its brand against Match Group multi-billion-dollar marketing budgets and global international distribution channels. Corporate rivalries in consumer mobile software match competitive dynamics we followed when Meta executed multi-billion dollar platform settlements.
Debt Restructuring and Shareholder Disillusionment
The $6.05 per share buyout price offers bittersweet closure for long-term Bumble shareholders. Investors who purchased shares near the $76 peak following the 2021 initial public offering are absorbing massive capital losses. Private equity firm Blackstone, which acquired a majority stake in Bumble parent company MagicLab in 2019 at a $3B valuation, took hundreds of millions off the table during the IPO but watched its remaining equity value erode over subsequent quarters.
The transaction will require formal approval from Bumble public stockholders and regulatory clearance from antitrust authorities. Given the significant premium offered over the trailing thirty-day average share price, institutional asset managers are expected to vote in favor of the deal, preferring immediate cash recovery over the uncertainty of an ongoing turnaround in public markets. The macroeconomic strains influencing corporate valuations across tech were detailed in our analysis of economists warning of systemic risks from corporate capital spending.
The Broader Reset Across Consumer App Investing
The fall of Bumble reflects a broader reckoning across consumer mobile software. For fifteen years, venture capital firms funded consumer mobile applications under the assumption that user growth could be monetized indefinitely through targeted advertising or micro-subscriptions. That era produced massive fortunes when smartphone adoption was exploding.
Today, consumer app markets are saturated. App store discovery is broken, smartphone users rarely download new applications, and privacy changes enacted by Apple have made user acquisition expensive. Venture investors have redirected their capital toward industrial computing, enterprise infrastructure, and custom silicon, leaving consumer software ventures struggling for financing. The $1.3B sale of Bumble confirms that the era of building multi-billion-dollar empires on simple mobile swipe mechanics is officially over. The capital shifts away from consumer apps toward hardware infrastructure were examined in our report detailing Crusoe securing $3B to expand physical computing hubs.
The Road Ahead for Whitney Wolfe Herd
Whitney Wolfe Herd return to private company leadership presents a challenging executive test. Having navigated the highs of a multi-billion-dollar IPO and the public scrutiny of collapsing market valuation, the founder must prove that she can reinvent the product that defined her career.
Taking Bumble off the public market provides the operational freedom required to rethink modern digital connection from the ground up. If Wolfe Herd and Ravi Gupta can build a platform that helps people connect in the physical world without turning romance into an exhausting video game, Bumble could pioneer the next era of social technology. If they fail, the company will be remembered as a cautionary tale of how quickly consumer fads can fade when technology loses touch with real human needs. The corporate mechanics of large private buyouts match patterns we documented when Lyft settled driver misclassification litigation, while broader consumer platform changes were tracked when TikTok reached state settlements over user safety controls.
Read More on TechRobust:
Umar Thariwat
 LinkedIn
Umar Thariwat
Expertise:Tech News Reporting, Tech Business Analysis, Economic Foundations, Market Trends, Digital Economy
Award:Rising Voice of the Year 2025
Thariwat is a Staff Writer and Reporter covering tech news and enterprise trends at TechRobust. Blending daily reporting with her ongoing academic background in economics, she analyzes earnings, digital market, and the commercial strategies powering the global tech sector.