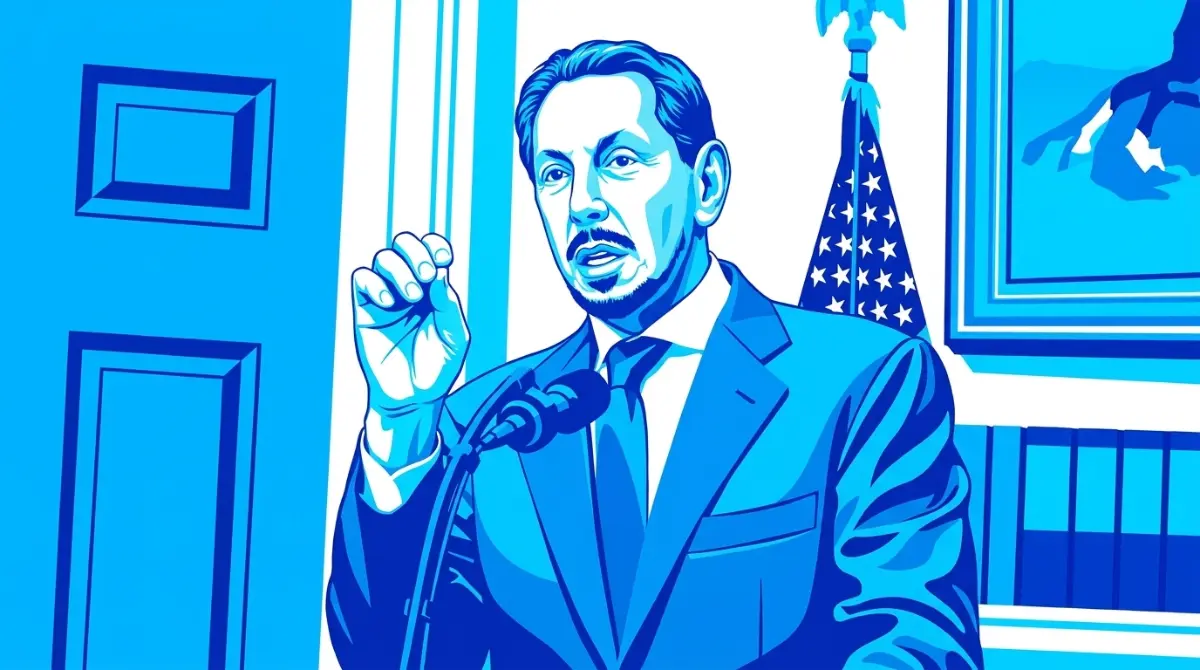


Oracle Executives See Nearly $1B in Stock Options Plunge
Oracle awarded its top leadership nearly $1B in equity compensation. By the close of the financial year, a sharp stock decline erased that entire value.
Umar Thariwat | 26 Sept. 2026 · 7 min read
When companies issue stock to their executives, the goal is to align corporate success with personal wealth. Oracle executed this exact strategy recently by granting co-founder Larry Ellison and his co-CEOs, Clay Magouyrk and Mike Sicilia, equity packages valued near $988M. The financial plan appeared completely sound when the documents were signed in late 2025. Yet, by the end of the fiscal year in May 2026, those massive equity grants held zero intrinsic cash value. The strike prices attached to the options sat far above the actual trading price of the shares on the open market, rendering the entire compensation package temporarily worthless.
The actual breakdown of this pay structure shows extreme wealth concentration at the top of the organizational chart. The board awarded Magouyrk a package worth $621.7M. Sicilia received grants valued at $248.7M. Ellison took home a package originally priced at $117.8M. The board granted the options when the stock was trading near its absolute peak. To convert these options into actual cash, the executives need the stock price to climb past a very strict exercise threshold. Ellison needs the stock to surpass $280 per share. His co-CEOs face an even steeper climb, needing the price to cross $308. With the stock recently dropping to $137, representing a severe 53 percent drop over the past twelve months, the path to a payout requires the company to double its current market valuation.
Aggressive Revenue Targets
The exact mechanics of the massive payout depend completely on future corporate sales. According to the proxy filing released on Friday, the $870M combined package handed to the two co-CEOs splits into two distinct categories. Eighty percent of the package functions as standard stock options resting on the $308 strike price. The remaining twenty percent relies strictly on highly aggressive revenue milestones. These performance awards only begin to unlock if the software giant pushes its non-GAAP revenue past the $100B mark by fiscal 2028. To receive the maximum possible payout, the company must hit a staggering $250B in total revenue. Considering the company posted $67.4B in revenue for the 2026 fiscal year, the leadership team must nearly quadruple their sales volume within two years to collect their full checks.
The executives did not walk away completely empty-handed this year. Despite the equity collapse, the board approved a $4.9M cash bonus for Ellison, Magouyrk, and Sicilia. Additionally, Ellison quietly abandoned his famous one dollar annual salary. The board raised his base pay directly to $950,000. These cash payments offer immediate liquidity, but they represent a tiny fraction of the wealth originally promised in the signed options contracts.
Connecting the Drop to Infrastructure Costs
A massive drop in shareholder value usually signals operational failure, but Oracle recently reported very strong revenue numbers. Cloud infrastructure sales jumped 77 percent. Total remaining performance obligations swelled to $638B. The company is successfully selling software. The financial drain is coming entirely from physical construction. Like other technology giants, the database company is spending heavily to build artificial intelligence data centers. The organization deployed $55.7B in capital expenditures during the last fiscal year, driving its free cash flow negative by $23.7B.
Investors watched this aggressive spending and aggressively sold off their shares, fearing the delayed returns on these massive physical investments. We previously saw exactly how expensive this construction phase gets when Oracle delayed payments on a massive $165B computing facility due to local power grid constraints in New Mexico. Wall Street hates uncertainty, and building physical buildings introduces massive geographical and political delays that simple software updates never face.
Defending the Pay Structure
The board of directors is defending the situation aggressively. In their latest proxy statement, they argued that the options losing their value proves the compensation system actually works. They insist that executives should only collect their money if regular shareholders also see their portfolios grow. Since the share price collapsed, the leaders receive nothing from the options. The board made no attempt to issue new, cheaper shares to make up for the loss, forcing the leadership team to fix the stock price if they want their bonuses.
Not every executive at the company suffered the exact same fate. Chief Financial Officer Hilary Maxson avoided the all-or-nothing risk of standard options. She chose to put $10.4M of her total equity award into restricted stock units. While those units did lose value alongside the broader market crash, dropping to roughly $7.7M by the end of the fiscal year, they still retain actual cash value. The restricted units guarantee a payout regardless of where the stock price lands, proving that safer compensation routes often beat aggressive option structures during volatile market cycles.
Internal Friction and Employee Morale
The conversation regarding executive pay arrives during a highly difficult period for the rank-and-file workforce. The proxy filing revealed that the median global compensation for regular Oracle employees fell from $98,899 to $94,740 over the last twelve months. The company also executed severe staff reductions across its cloud divisions. Asking employees to accept lower pay and job insecurity while simultaneously printing nearly a billion dollars in potential bonuses for three men creates severe internal tension. This disconnect between the executive suite and the engineering floor is a growing problem across the entire software industry, mirroring the exact friction seen when major technology firms cut thousands of jobs to fund server purchases.
Funding the Physical Cloud
To finance the $55.7B capital expenditure bill, the corporate treasury worked overtime. The finance department raised $43B by selling senior notes to the debt markets. They followed that by executing a massive $20B equity sale, flooding the market with new shares priced at $141 each. When a corporation sells $20B worth of new stock, it immediately dilutes the value of the existing shares. Institutional investors sold their holdings rapidly, punishing the stock price. The company is actively betting its entire balance sheet on the belief that enterprise clients will pay heavy premiums for access to their new data centers.
Federal regulators are watching these massive financial shifts closely across the entire sector. We covered this growing federal scrutiny recently when discussing how the SEC demands investment firms prove ownership of private startup shares, proving that government agencies want better visibility into how technology companies fund their aggressive expansions.
Personal Leverage and External Ambitions
The plunging stock price creates secondary problems for Ellison. The co-founder frequently uses his massive corporate ownership as collateral for personal loans. The recent financial disclosures show he pledged 413 million shares to secure personal debt. At the current depressed stock price, that collateral is worth roughly $9.2B. He uses this borrowed cash to fund external ventures, including heavily backing his son David Ellison in an aggressive $111B takeover attempt of Warner Bros. Discovery.
When the stock price drops by half, the banks holding those shares as collateral get very nervous. If the price falls too far, lenders can issue a margin call, forcing the executive to sell shares directly into a falling market. The corporate governance committee officially stated that these personal loan arrangements pose no risk to the wider shareholder base, but financial analysts monitor massive equity pledges closely.
The pressure on the new co-CEOs is immense. Magouyrk and Sicilia inherited the leadership roles from Safra Catz just one year ago. They are now tasked with steering a massive enterprise software company through the most expensive infrastructure buildout in modern history. If they succeed, the stock price will recover, and their massive option packages will trigger, making them incredibly wealthy. If they fail to convince the market, those options will expire worthless, and the board will likely look for new leadership. The race to monetize digital intelligence is forcing every major vendor to rethink their business model entirely, a shift highly visible as Apple actively targets enterprise AI costs to lure corporate clients away from expensive server contracts.
Read More on TechRobust:
Umar Thariwat
 LinkedIn
Umar Thariwat
Expertise:Tech News Reporting, Tech Business Analysis, Economic Foundations, Market Trends, Digital Economy
Award:Rising Voice of the Year 2025
Thariwat is a Staff Writer and Reporter covering tech news and enterprise trends at TechRobust. Blending daily reporting with her ongoing academic background in economics, she analyzes earnings, digital market, and the commercial strategies powering the global tech sector.