

Safaricom Expands M-PESA Into Wealth and Insurance
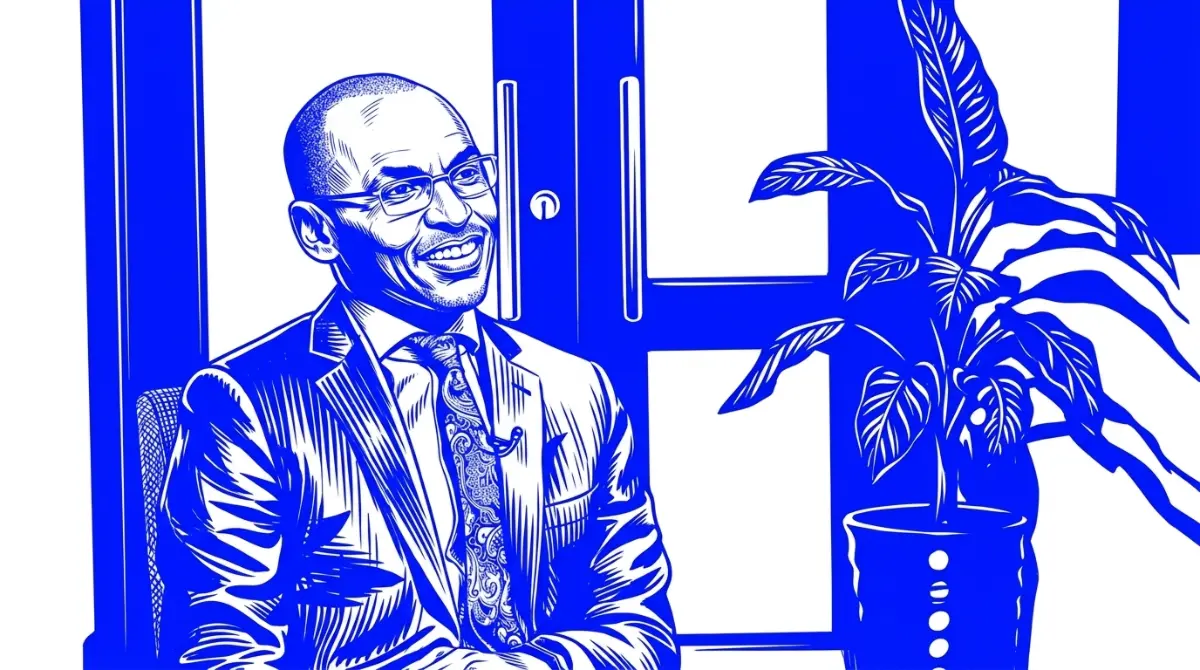
Safaricom Chief Executive Officer Peter Ndegwa announced that mobile money service M-PESA is branching out into savings, wealth management, and micro-insurance, transforming Kenya dominant payment platform into an integrated financial supermarket while managing international expansion losses and domestic ownership battles.
Inioluwa Ademidun | · 9 min read
Mobile money in East Africa began twenty years ago as a simple tool to send phone airtime between relatives. A worker in Nairobi bought digital credits and texted them to parents in rural villages, who redeemed the codes for paper shillings at local general stores. That basic payment loop grew into an economic powerhouse. Safaricom flagship platform M-PESA now processes roughly 150 million transactions every twenty-four hours, serving as the commercial backbone for Kenya economy. Yet relying purely on peer-to-peer transfer fees has reached natural limits. Central banking authorities have introduced strict fee caps, while competing mobile networks and commercial banks have eliminated charges on small transactions to win customers. Safaricom moved to redefine its financial future on Friday, October 23, 2026. Speaking in a broadcast interview with CNN, Safaricom Chief Executive Officer Peter Ndegwa confirmed that M-PESA is expanding beyond payments into personal savings, wealth management, and micro-insurance products. The transition aims to turn the telecommunications product into a full-scale financial services company, challenging traditional banks while managing corporate ownership disputes in court. The strategic pivot arrives as mobile operators diversify revenues, an operational trend visible when Airtel Money adjusted its public offering targets.
The announcement details a sweeping corporate evolution. M-PESA is already Safaricom largest revenue generator, with sales climbing 13.4% to KES 182.7B in the financial year ending March 31, representing 45.6% of the company total service income. Still, management recognizes that mature telecommunications platforms must offer higher-margin financial products to sustain growth. By offering structured savings accounts, collective investment trusts, and low-cost health and crop insurance, Safaricom is targeting the millions of Kenyans who use mobile money daily but remain excluded from formal banking halls. Ndegwa reiterated the company ambition to become Africa leading purpose-led technology firm, using automated data layers to underwrite micro-loans and detect transaction fraud. The expansion comes as Safaricom navigates complex cross-border investments in Ethiopia and defends its corporate governance against domestic court challenges over state share sales. The convergence of telecommunications and consumer banking matches developments we examined when PalmPay pursued capital to expand digital banking services.
Escaping the Commodity Trap of Basic Payments
To understand why Peter Ndegwa is moving M-PESA into wealth management and insurance, one must look at the margin compression threatening basic mobile payments. For fifteen years, Safaricom enjoyed exceptional profit margins by charging fees on every cash deposit, phone transfer, and merchant withdrawal. Peer-to-peer transfers were a cash cow that funded mobile tower construction and fiber optic backbones across Kenya.
That revenue model has encountered mounting political and regulatory friction. The Central Bank of Kenya and parliamentary consumer committees have pressured telecommunications providers to slash transaction fees, pointing out that high payment charges punish low-income households. Furthermore, consumer habits are shifting: users treat simple cash transfers as a free public utility rather than a luxury service. To protect operating profits, Safaricom must move up the financial value chain. Wealth management and insurance represent lucrative territory: collecting asset management fees on mutual funds and underwriting premiums on health insurance generates predictable, recurring revenues that cannot be easily undercut by rival payment apps. By embedding investment options directly inside the M-PESA smartphone app, Safaricom allows users to invest as little as one hundred Kenyan shillings into government bonds or money market funds with a single biometric touch. The shift toward wealth management software reflects trends we analyzed in our coverage of fintech platforms dismantling traditional fee models.
The Ethiopia Bet: Losses Narrow Across the Northern Border
A central pillar of Safaricom regional strategy is its high-stakes investment in Ethiopia. Entering Ethiopia in 2021 was the most expensive expansion in Safaricom history, requiring billions of dollars to build brand-new cellular base stations, secure national spectrum licenses, and establish a greenfield telecommunications network in Africa second-most populous nation.
The Ethiopian expansion was complicated by civil conflict, foreign exchange shortages, and sudden currency devaluations. Ndegwa noted that the Ethiopian birr dropped 23.7% against the US dollar over the past year, inflating foreign debt servicing expenses for the regional subsidiary. Despite these macroeconomic shocks, the Ethiopian operational numbers are showing clear operational progress. The 90-day active customer base for M-PESA in Ethiopia jumped by 119.4% to reach 5.2M subscribers. Even more significant is the financial recovery: operating losses measured by earnings before interest, tax, depreciation, and amortization narrowed by 64.8%, shrinking from KES 43B down to KES 15.1B. Management projects that Ethiopian startup losses will continue to decline this fiscal year as network coverage expands across regional cities. Ndegwa described the Ethiopia rollout as one of the defining achievements of his six years leading Safaricom, expressing confidence that Ethiopia will eventually replicate Kenya commercial success. The operational discipline required to manage large infrastructure projects was detailed in our review of Airtel Africa network investments.
Comparing Financial Service Offerings Across East African Telecoms
| Service Domain | Traditional M-PESA Payment Rails | Expanded Safaricom Wealth & Insurance Suite |
|---|---|---|
| Primary Revenue Engine | Metered fees per transfer, cash-out, and merchant pay | Management fees on assets and recurring insurance premiums |
| User Capital Relationship | Transitory zero-interest wallet balances | Compounding interest-bearing savings and money market investments |
| Fraud Prevention Logic | Rule-based limits and manual customer complaints | Automated data layer parsing 150 million daily transactions |
| Merchant Credit Access | Basic consumer overdrafts (Fuliza consumer) | Fuliza Ya Pochi targeting one million informal traders |
| Regional Footprint | Dominant Kenyan domestic footprint | Multi-country network scaling into 5.2M Ethiopian accounts |
The comparison matrix demonstrates how Safaricom is building a sticky financial relationship with its users. Moving from transactional payment processing to custodial asset management ensures that customer funds remain inside Safaricom accounts for months rather than flowing out to commercial bank accounts within hours.
The High Court Legal Cloud Over Company Ownership
While management executes its commercial expansion, a cloud of legal uncertainty hangs over Safaricom corporate ownership structure. On September 15, Kenya High Court voided the government sale of a 15% equity stake in Safaricom to South African telecommunications conglomerate Vodacom.
The disputed transaction, which took place earlier this year, allowed Vodacom to expand its effective ownership in Safaricom from 35% to 55%, giving the multinational entity absolute voting control over Kenya most valuable commercial asset. The High Court ruled that the state privatization process lacked mandatory public participation, violated constitutional procurement guidelines, and amounted to an unapproved corporate takeover. The Kenyan government has appealed the judicial ruling, informing the Court of Appeal that the KES 204.3B ($1.58B) received from Vodacom was deposited into national budget accounts and is completely non-refundable. Ndegwa has maintained a neutral public posture throughout the courtroom drama, focusing on operational execution while assuring international investors that daily commercial activities remain unaffected by shareholder disputes. Nevertheless, the ownership battle creates governance headaches for the board, complicating long-term capital allocation choices. Sovereign regulatory disputes and ownership reviews match patterns we tracked when regulators audited ownership records for private shares.
Micro-Merchant Credit and the Fuliza Ya Pochi Rollout
Alongside wealth management and insurance, Safaricom is deepening its merchant credit operations. On Friday, the company announced the launch of Fuliza Ya Pochi, an automated credit overdraft service specifically engineered for informal micro-merchants.
Over the past four years, millions of small Kenyan vendors: roadside vegetable sellers, motorcycle taxi riders, and hair salon operators: adopted Pochi La Biashara, a separate business wallet that keeps merchant revenues isolated from personal funds. However, when an informal merchant needed to purchase fresh inventory before morning sales arrived, they faced cash shortfalls. Fuliza Ya Pochi allows registered merchants to complete supplier transactions even when their digital wallet balance is zero, providing instant micro-loans based on historical transaction volumes. By extending credit lines directly to more than one million micro-merchants, Safaricom addresses a persistent working capital shortage while earning interest on micro-borrowings. The focus on informal merchant finance mirrors financial inclusion models we followed when Remita launched mobile tools for retail merchants.
AI Data Layers and the Fight Against Digital Fraud
Processing 150 million transactions each day creates an immense cybersecurity responsibility. Digital fraudsters and identity theft rings target mobile money users through social engineering schemes, fake SIM swaps, and automated phishing text messages.
Ndegwa emphasized that manual security teams cannot monitor hundreds of millions of daily transactions effectively. To protect account integrity, Safaricom deployed automated software layers that analyze transaction telemetry in real time. The software inspects transaction velocity, device identification signatures, and geographic location data. If an account suddenly initiates an unusually large transfer from a new mobile device in an unfamiliar town at three in the morning, the system flags the transaction, pausing settlement until the user verifies their identity through voice recognition or biometric confirmation. The automated data layer cuts fraud losses while ensuring that legitimate transactions clear without manual delays. Automated fraud management systems across enterprise networks match architectures we explored in our report on cybersecurity tools defending against automated attacks.
Challenging Kenya Legacy Banking Establishment
M-PESA expansion into savings, investments, and insurance represents a direct competitive challenge to traditional commercial banks like KCB Bank, Equity Bank, and NCBA. For two decades, commercial banks coexisted with Safaricom by acting as backend liquidity partners: providing settlement accounts while Safaricom handled retail payments.
By moving into wealth management and insurance directly, Safaricom is cutting into traditional banking revenue streams. An individual who can earn attractive yields on a money market fund inside the M-PESA app has little reason to open a traditional bank deposit account. Commercial bank executives have lobbied the Central Bank of Kenya to subject Safaricom to identical capital adequacy ratios and banking reserve rules, arguing that an unregulated telecommunications monopoly threatens the stability of the domestic financial system. Safaricom counters that it partners with regulated asset managers and insurance underwriters, ensuring that all financial products comply with domestic statutory regulations. The competitive duel between mobile money operators and legacy lenders was examined in our review of Kenswitch launching domestic payment card alternatives.
The Future of African Mobile Financial Supermarkets
Safaricom transformation of M-PESA proves that mobile money is evolving from a convenient payment utility into a complete financial operating system. By delivering savings, investment, micro-insurance, and merchant credit across a single application, the Kenyan operator is demonstrating how technology can democratize sophisticated financial tools for millions of unbanked citizens.
The road ahead will require careful navigation: resolving ownership disputes in domestic courts, absorbing initial expansion losses in Ethiopia, and defending payment rails against cyber threats. If Peter Ndegwa and his executive team succeed, M-PESA will build more than a profitable telecommunications company; it will establish an enduring blueprint for financial empowerment across emerging economies. As African consumers seek economic security in volatile global markets, the institutions that prosper will not be those that simply move money, but those that help everyday citizens save, protect, and grow their wealth for generations to come. Mobile network scaling across regional hubs was also tracked when MTN expanded mobile money operations across Nigeria, alongside broadband and telecom updates detailed in our analysis of 5G network growth across major cities.
Read More on TechRobust:
Inioluwa Ademidun
 LinkedIn
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.