

 LinkedIn
 Ugandan Startup XenFi Helps Hotspot Operators Sell Wi-Fi
Taja Tops 50,000 Users Across Seven African Markets
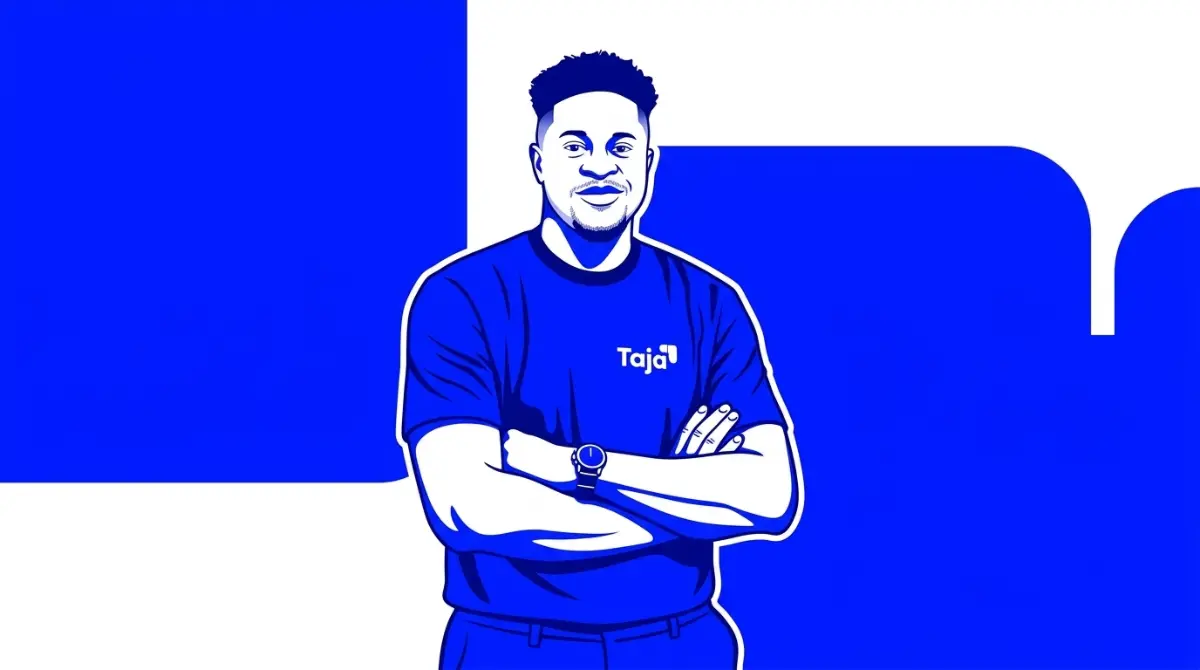
Pan-African payments startup Taja passed 50,000 active customers across seven regional countries, handling millions in monthly transactions through multi-currency accounts, virtual payment cards, and international payment settlement networks connecting Africa to Western commercial centers.
Inioluwa Ademidun | · 7 min read
Moving money between African nations remains one of the most expensive financial exercises in the world. When an independent graphic designer in Lagos completes an assignment for an advertising agency in Nairobi, receiving payment often requires waiting five business days for commercial bank wires to clear through correspondent banks in London or Frankfurt. Currency exchange fees eat up ten percent of the invoice value, while local banking limits prevent workers from spending foreign earnings online. That financial friction has kept millions of young African creators and merchants locked out of global commerce. Pan-African financial technology platform Taja moved to dismantle those barriers on Tuesday, October 27, 2026. The company announced that it surpassed 50,000 active users across seven African markets, processing millions of dollars in monthly transaction volume barely two years after opening its cross-border payment platform. The milestone demonstrates strong consumer appetite for borderless financial tools, continuing regional financial growth we tracked when African tech ventures reported strong quarterly funding totals.
The startup achieved rapid growth by building a multi-currency payment platform engineered for modern commercial needs. Launched in 2024 by Chief Executive Officer David Orovwiroro, Taja provides individual consumers, freelancers, and small business enterprises with unified financial accounts. Users can hold, convert, and transfer funds across multiple domestic currencies alongside the United States dollar, British pound, and euro. The platform operates across seven major regional markets: Nigeria, Ghana, Kenya, Senegal, South Africa, Benin, and Ivory Coast. Beyond basic peer-to-peer transfers, the platform issues virtual debit cards for international software subscriptions and provides digital asset settlement options for merchants seeking protection against regional currency drops. Orovwiroro explained that cross-border finance should function like sending a mobile message rather than solving a banking maze. The startup rapid adoption matches patterns we analyzed when PalmPay pursued capital to expand digital banking services.
The Freelance and Creator Boom Driving Borderless Demand
To grasp why Taja reached 50,000 active users in twenty-four months, one must examine the demographic transformation reshaping African labor. Sub-Saharan Africa possesses the youngest population in the world, with millions of educated graduates entering the job market each year.
Faced with high local unemployment, young Africans are looking outward: working as remote software developers, digital marketers, voiceover artists, and video editors for international clients in North America, Europe, and the Middle East. Traditional commercial banks in Africa were built for physical import-export merchants who trade containerized cargo, not for twenty-two-year-old freelancers receiving five-hundred-dollar payments from London design firms. International platforms like PayPal frequently restrict African accounts from receiving incoming payments, while local bank debit cards carry strict foreign currency spending limits of twenty dollars per month. Taja stepped into that financial void. By offering instant foreign currency receiving accounts in the user name, Taja allows a Nigerian animator or a Kenyan copywriter to receive direct bank deposits from overseas clients, convert funds at transparent exchange rates, and spend money locally through domestic mobile money channels. Financial tools supporting distributed workforces were explored in our analysis of Verto and Visa launching multi-currency corporate cards.
The Seven-Market Footprint: Bridging Francophone and Anglophone Africa
A major operational achievement for Taja is bridging the historical divide separating English-speaking and French-speaking African economies. African financial technology has historically suffered from regional fragmentation: startups in Nigeria and Kenya focused on English-speaking markets, while ignoring neighboring Francophone nations.
Taja integrated its payment rails across both economic zones simultaneously. Operating in Senegal, Ivory Coast, and Benin alongside Ghana, Nigeria, and Kenya allows the platform to facilitate commercial trade between West Africa distinct monetary zones. A merchant in Cotonou can purchase clothing inventory from a manufacturer in Aba, settling the transaction through Taja in West African CFA francs or Nigerian naira within seconds. The system removes the foreign exchange penalty that previously forced merchants to buy physical dollar notes from black-market street dealers before crossing borders. By linking mobile money systems like Wave and Orange Money in Francophone nations with bank networks in Nigeria and M-PESA in Kenya, Taja built an integrated commercial corridor. Cross-border trade developments were also detailed in our coverage of how Nomba secured debt financing for Central African trade.
Comparing Cross-Border African Payment Providers
| Platform Provider | Active Market Reach | Supported Fiat Currencies | Virtual Card Issuance | Digital Asset Settlement |
|---|---|---|---|---|
| Taja | 7 African nations + UK / US rails | NGN, GHS, KES, XOF, ZAR, USD, GBP, EUR | Instant multi-currency virtual Visa | Integrated stablecoin payout options |
| Chipper Cash | Multi-country African footprint | Regional African currencies + USD | Virtual cards supported in select hubs | Cryptocurrency trading features |
| LemFi | Diaspora remittance corridors | Inbound diaspora currencies to Africa | Limited domestic consumer cards | Strictly regulated fiat rails |
| Grey Finance | East and West African hubs | USD, GBP, EUR foreign accounts | Virtual foreign spending cards | Pure banking settlement channels |
| Geegpay (Raenest) | Freelancer-focused African markets | Foreign client receiving accounts | USD virtual corporate cards | Limited third-party asset payouts |
The comparative data illustrates how Taja carved out market space by focusing on both inbound international payments and intra-African trade. While diaspora apps like LemFi concentrate exclusively on sending money from London or Toronto back to families in Africa, Taja enables two-way transactions within the continent itself. An entrepreneur in South Africa can pay a supplier in Ghana as easily as receiving funds from an employer in New York. Payment infrastructure modernizations match regulatory updates we tracked when South Africa opened payment rails to fintech companies.
Digital Asset Settlement and Currency Protection
Operating a financial platform across sub-Saharan Africa requires confronting currency volatility. Over the past twenty-four months, sharp devaluations in the Nigerian naira and Ghanaian cedi wiped out business capital for merchants holding domestic bank deposits.
Taja addressed this risk by incorporating digital asset rails into its backend infrastructure. The platform enables businesses to settle cross-border invoices using dollar-backed stablecoins. When an international client pays an invoice, the African recipient can choose to hold funds in a digital dollar wallet rather than converting immediately into a local currency that may lose value by morning. When the user needs to pay rent, buy groceries, or cover local payroll, they convert the precise amount required into local mobile money or bank accounts in seconds. By acting as a bridge between traditional banking networks and digital currency rails, Taja provides everyday citizens with tools to protect their purchasing power against inflation. Stablecoin payment integrations across global commerce were analyzed in our report on institutional payment partnerships and stablecoin settlement rules.
Regulatory Compliance and Anti-Money Laundering Frameworks
Expanding across seven distinct African jurisdictions presents immense regulatory and compliance hurdles. Each country enforces separate foreign exchange rules, central bank reporting guidelines, and anti-money laundering mandates.
Taja navigates this regulatory patchwork through a hybrid licensing strategy. In core markets, the company operates through direct partnerships with licensed domestic commercial banks and regulated payment service providers. In partner jurisdictions, transactions clear through licensed local financial institutions that handle domestic currency settlement and file required regulatory disclosures with central banking authorities. Taja proprietary software handles identity verification: using automated biometric screening tools that check national identity databases, such as the Bank Verification Number in Nigeria and the Ghana Card in Accra, in real time. The platform applies automated transaction monitoring algorithms that flag suspicious transaction velocities or unusual volume spikes, pausing transfers before illicit funds cross borders. Demonstrating strict compliance safeguards is mandatory for expanding cross-border payment platforms, continuing regulatory standards we followed when central bank rules targeted financial market concentration.
The Road to One Hundred Thousand Users
Surpassing 50,000 customers provides Taja with the transaction volume and fee revenues needed to accelerate its international roadmap. David Orovwiroro confirmed that the startup is planning to expand its footprint into Central and Southern Africa, preparing launches in Rwanda, Uganda, and Zambia.
The company is also building merchant tools tailored for commercial enterprises: introducing automated invoice factoring, batch payroll disbursement for multinational African startups, and checkout widgets for online retailers. As African commercial trade expands under the African Continental Free Trade Area, the demand for fast, affordable, transparent payment infrastructure will continue climbing. Taja has proven that young, agile technology ventures can build reliable financial rails that challenge legacy banking monopolies. By connecting African workers and merchants directly to the global economy, Taja is demonstrating that the future of African commerce will be borderless, digital, and built for everyone.
Read More on TechRobust:
Tags:TajaCross Border PaymentsAfrican fintechDavid Orovwirororemittancesvirtual cardsmulti currency wallets
Inioluwa Ademidun
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.
Related Stories
Ugandan Startup XenFi Helps Hotspot Operators Sell Wi-Fi Airtel Money Revenue Jumps 34% to $830M Post-IPO
 Safaricom Expands M-PESA Into Wealth and Insurance